 look news india
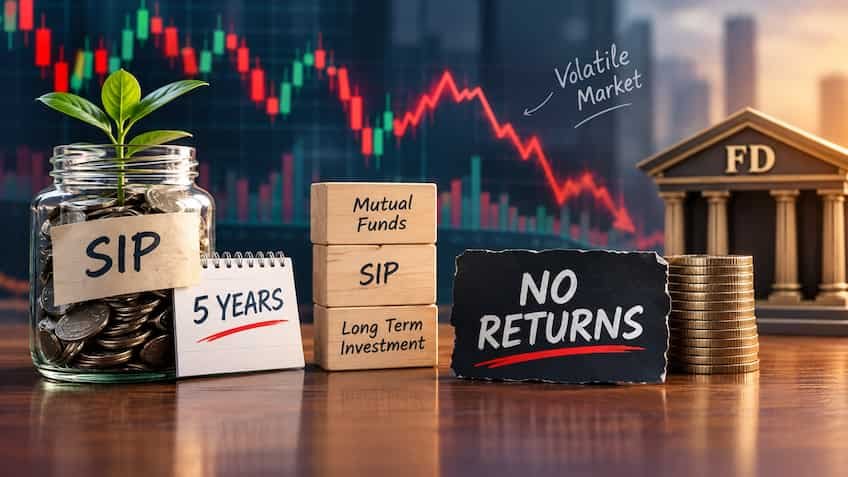
Amidst the ongoing fluctuations in the stock market for the last few months, global geopolitical tensions and valuation concerns, lines of worry have started appearing on the forehead of mutual fund investors. Many investors, who have started systematic investment plans (SIPs) in equity mutual funds after seeing excellent returns in the last three to five years, are now asking the question whether fixed deposits (FDs) are outweighing equity SIPs from a 5-year perspective in the current consolidation phase of the market?
The biggest feature of equity mutual funds is that it is a medium for wealth creation in the long term, but in the medium term (3 to 5 years) it is completely affected by the stock market cycle. When the market slows down after reaching new highs or goes through a correction, there is a sudden sharp decline in XIRR returns of recently started SIPs.
In contrast, interest rates in bank fixed deposits remain fixed and safe. In recent times banks and small finance banks have offered guaranteed interest ranging from 7% to 8.5%. In such a situation, when the 5-year equity SIP return of a conservative investor comes down to the range of 8% to 9% due to market decline, he feels that keeping the money in FD without any risk was safer and beneficial.
| Criteria | mutual fund equity sip | Bank Fixed Deposit (FD) |
| Return Type | Market-linked (variable 10%-14%) | Fully Fixed and Guaranteed (6.5%-7.5%) |
| security of capital | Subject to market risk (volatility possible) | Insured by DICGC up to ₹5 lakh |
| protection against inflation | Historically capable of beating inflation by 5-6% | Real returns after tax and inflation are zero or 1-2% |
| Taxation | 12.5% LTCG above ₹1.25 lakh | As per tax slab (30% slab has heavy tax drag) |
If an investor deposits ₹10,000 per month for 5 years (total investment ₹6,00,000), the approximate figures in both the modes come out as:
-
Bank FD (assuming 7.0% per annum interest): The total maturity amount after 5 years will be approximately ₹7,15,929. That means the total interest benefit will be approximately ₹ 1,15,929. If the investor falls in the 30% tax slab, the net profit in hand after deducting tax further reduces.
-
Equity SIP (assuming 12.0% expected long-term returns): After 5 years the total amount can reach approximately ₹8,24,864. That means the total capital gain will be approximately ₹ 2,24,864. 12.5% LTCG tax is applicable only on the additional profit after exemption of ₹1.25 lakh.
Thus, even if the market remains around the general historical average, equity SIPs outperform FDs even over a 5-year period. But if there is a big correction of 15-20% in the market at the end of the 5th year, then the SIP profit can reduce significantly, which is called ‘Sequence of Returns Risk’.
For senior citizens or those who want to withdraw money within 1 to 3 years, FD is most suitable. But if seen from the perspective of 5 years or more, the biggest enemies of FD are tax and inflation.
-
For a person in the 30% income tax bracket, the net post-tax return on an FD of 7.0% comes out to be around 4.9%.
-
If the retail inflation (CPI) in the country remains around 5%, then the money kept in FD starts losing its purchasing power over time.
-
In Equity SIP, tax is levied only at the time of redemption, thereby providing full benefit of compounding on both principal and interest for full 5 years.
-
Allocation as per target time horizon: If you need money in less than 3 years (like child fees, home loan downpayment), then do not take risks in the stock market and choose bank FDs or liquid funds.
-
Perspective of 5 years or more: If the goal is 5 to 7 years away or beyond (like retirement or a long-term fund), do not stop the SIP due to short-term market fluctuations. During recession, more units are available through SIP at cheaper NAV (Rupee Cost Averaging).
-
Balanced Asset Allocation: Keep 20-30% of your total savings in bank FDs for emergencies and capital protection and invest the remaining surplus in index funds or flexi-cap SIPs for long term.