 look news india
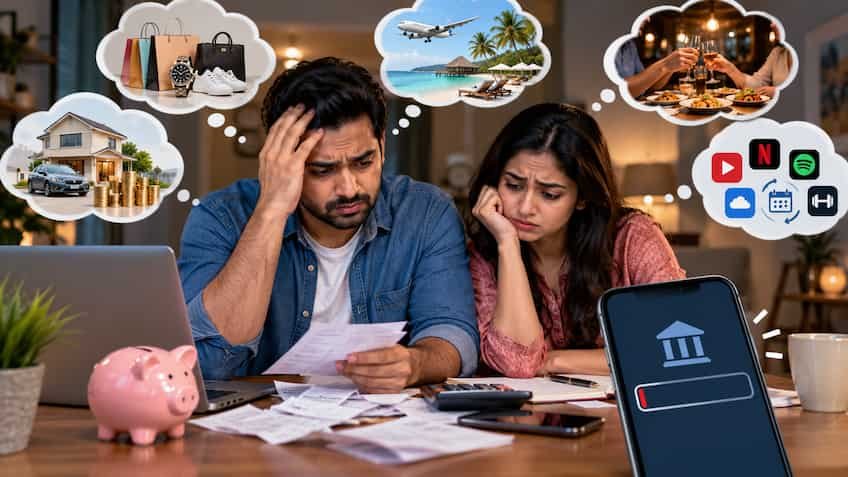
These days, a strange confusion is increasing rapidly among working couples living in metros and big cities. There is double income in the house, both the partners are working on good packages, yet in the last week of the month the bank balance becomes almost zero. Seeing the credit card bills, we sweat and do not understand where the combined income of lakhs of rupees has been spent. This has become a common problem for working couples living in cities like Delhi-NCR, Mumbai, Bengaluru, Lucknow or Hyderabad. According to finance experts, the reason for this is not low income, but lack of financial coordination and basic budgeting.
Hesitation to talk openly about money is still seen in Indian families. When both partners are earning, it is often assumed that expenses are managed automatically. One partner is paying the house rent and electricity bill, while the other is paying the expenses of groceries and eating out. But no one sits and decides what the total savings should be in a month. There is no clear outline for future goals like buying a new house, buying a car, retirement or children’s higher education. Unless a joint blueprint of earnings and expenditure is prepared, money will continue to flow like water.
It is natural for lifestyle expenses to increase as income increases, but increasing it excessively becomes the main cause of financial crisis. In the language of economics, this is called ‘lifestyle creep’ or ‘lifestyle inflation’. Going to expensive cafes on weekends, upgrading to a new gadget or smartphone every six months, shopping for branded clothes and spending lavishly on lavish holidays seen on social media completely spoils the budget. Partners keep spending thinking that everything will be sorted out as soon as the next salary comes, but in reality they get trapped in a maze where the scope for saving is eliminated.
Credit cards are for convenience, but lack of discipline makes them the biggest debt trap. Many couples fall into the trap of ‘No Cost EMI’ and ‘Buy Now Pay Later’ and buy things which they do not need immediately. When the salary comes on the first of the month, a large part of it is directly deducted from credit card bills and personal loan installments. The amount left in hand is less even for daily household expenses. After this, the credit card is swiped again to survive the remaining days, due to which this cycle never ends.
Generally, dual income couples feel that even if one loses his job or faces any crisis, everything will be taken care of with the income of the other. This overconfidence can prove costly. In case of medical emergency, sudden job loss or any major crisis in the family, when there is not enough emergency fund (at least 6 months of expenses), one has to break the investment or take loan at huge interest. Additionally, lack of adequate term insurance and comprehensive health insurance on both partners can also wipe out all the hard-saved capital in one fell swoop.
Most working couples rush to find ways to save tax in the last months of the financial year, i.e. between January and March. Without thinking, such policies or schemes are taken whose returns do not even beat the inflation rate. Apart from this, leaving the savings lying only in the savings account is also a big mistake, because the money lying in the savings account is not only at risk of being spent but the interest earned on it is less than inflation. If you do not invest regularly in Systematic Investment Plan (SIP), Mutual Funds, Public Provident Fund (PPF) and Equity, you do not get the benefit of compounding.
To get out of this situation, husband and wife should together make a transparent financial plan. For this, the rule of 50:30:20 is considered to be most effective, in which 50 percent of the total income should be spent on essential needs (rent, ration, bills), 30 percent should be spent on lifestyle and personal desires, and at least 20 percent should necessarily go to investments and savings. Both the partners should jointly open a joint bank account in which the amount of common household expenses and savings can be deposited, while some part can also be kept in their respective personal accounts. Sitting down at the end of every month to review expenses and plan for the coming month is one of the strongest habits for keeping your bank balance safe.