 look news india
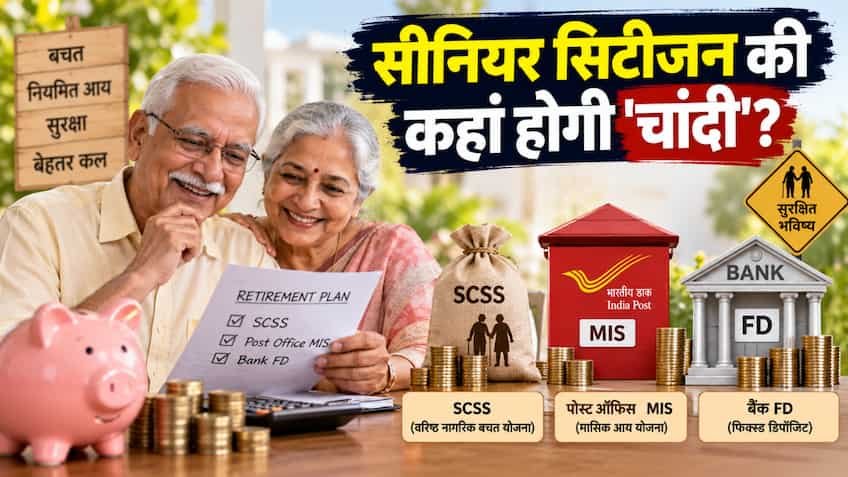
After retirement, the priority of every senior citizen is to protect their lifetime hard-earned money without any market risk and get regular monthly or quarterly income from it. There are three major and most popular options for senior citizens in the Indian savings market—Senior Citizen Savings Scheme (SCSS), Post Office Monthly Income Scheme (POMIS), and Senior Citizen Fixed Deposit (Bank FD) of banks. There is a big difference in the interest rates, payment methods and tax rules of these three schemes, due to which there is a difference of lakhs of rupees in the return amount.
Before choosing a scheme, it is important to know how much money can be invested in which scheme and how much return the government or banks are giving on it:
-
Senior Citizen Savings Scheme (SCSS): This government-backed scheme currently offers the highest annual interest rate of 8.2% to senior citizens. In this a person can invest maximum up to ₹ 30 lakh.
-
Post Office Monthly Income Scheme (POMIS): This post office scheme offers an annual interest rate of 7.4%. In this, a maximum of ₹ 9 lakh can be deposited in a single account and a maximum of ₹ 15 lakh can be deposited in a joint account.
-
Bank Senior Citizen FD: Major government and private banks (like SBI, HDFC, ICICI) are offering annual interest ranging from 7.25% to 7.60% on 5 year FD to senior citizens. There is no official upper limit for investment in this.
If a senior citizen invests a lump sum capital of ₹ 15 lakh in any one of these three options for 5 years, then the mathematics of regular income is as follows:
-
SCSS (8.2% interest): On ₹15 lakh, you get a guaranteed income of ₹30,750 every 3 months (quarter). The total income from interest alone in 5 years is ₹ 6,15,000.
-
Post Office MIS (7.4% interest): A joint account of ₹15 lakh yields a fixed pension-like income of ₹9,250 every month. The total interest in 5 years comes to ₹5,55,000.
-
Bank FD (average 7.5% compounding): If the interest is not taken into account on quarterly basis and is allowed to be compounded on maturity, then the amount of ₹ 15 lakh becomes approximately ₹ 21,74,900 after 5 years, that is, the total interest received is approximately ₹ 6,74,900. If quarterly payment is taken then the income is around ₹ 28,125 per quarter.
It is extremely important to keep track of tax deductions along with returns:
-
SCSS: In this, the benefit of tax deduction up to ₹ 1.5 lakh is available under Section 80C of Income Tax on the original amount deposited. However, the interest earned is fully taxable and TDS is deducted on annual interest above ₹50,000.
-
Post Office MIS: There is no tax benefit under Section 80C in this. The monthly interest received is added to your total income, although the post office does not deduct TDS on it.
-
Bank FD: A normal 5-year tax saver FD gets Section 80C exemption, but quarterly interest withdrawal is not allowed. 80C is not available in normal regular FD and banks deduct TDS on interest more than ₹ 50,000 under section 80TTB.
If you want the highest guaranteed interest and 80C tax exemption every three months, SCSS is unquestionably the best option. If your priority is to have regular pension to meet household expenses every month, then Post Office MIS proves to be the most suitable. At the same time, if you do not need regular income immediately and want to grow your capital faster through compounding, then 5-year cumulative FD of banks gives the highest profits.