 look news india
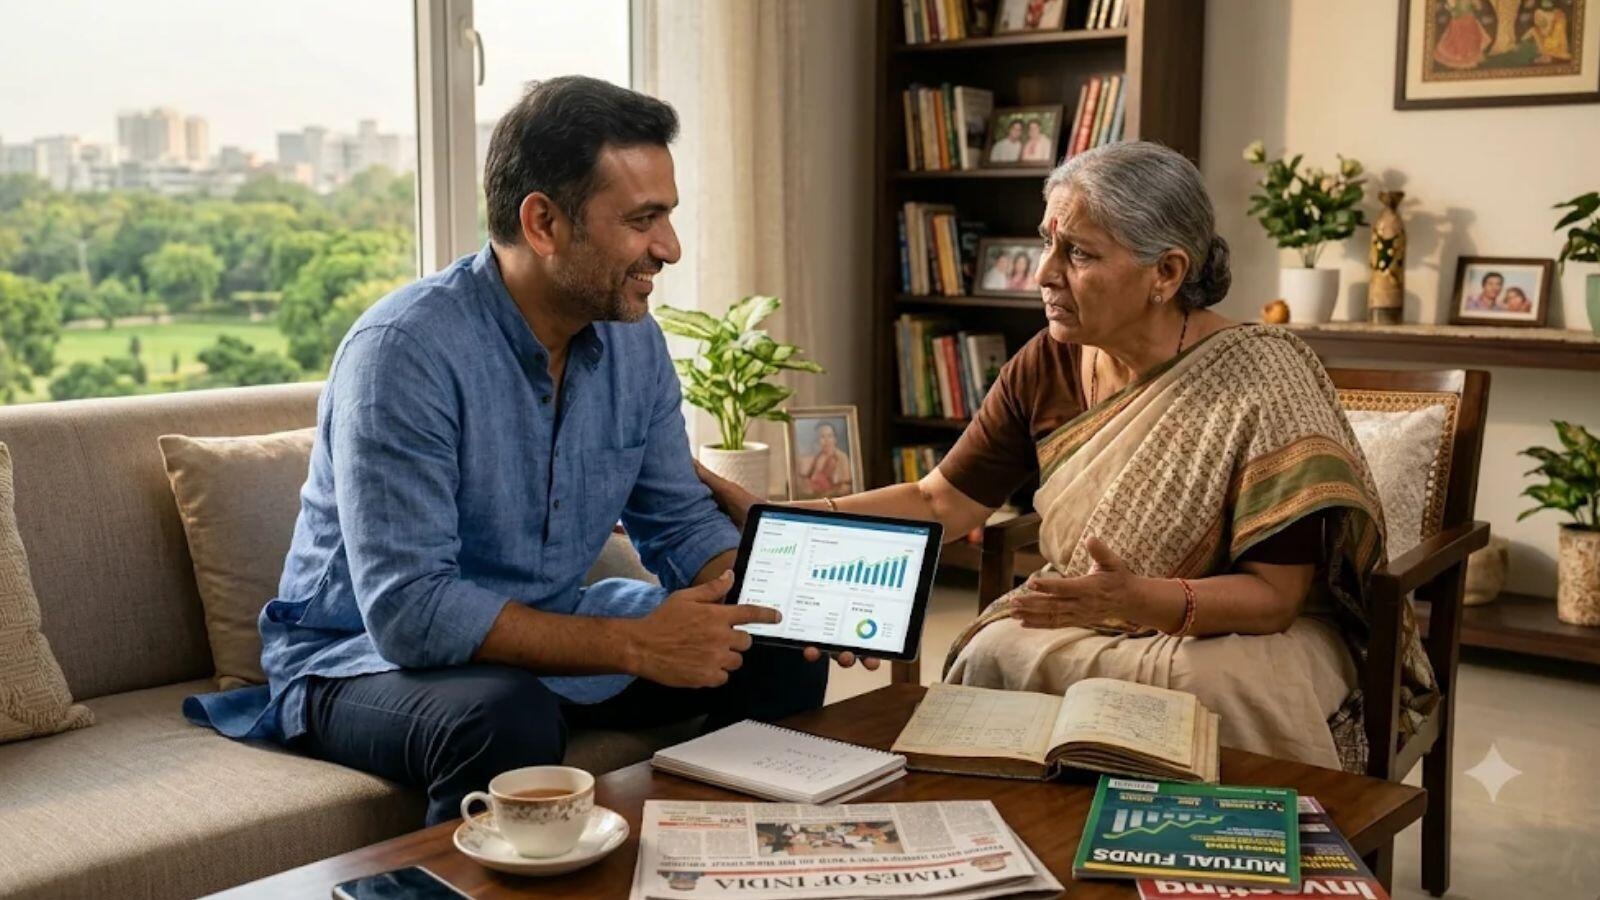
“Son, how old are you now? It is not right to sit at home empty-handed, God forbid, if some need arises tomorrow, what will you do? Go and find some decent job…” This dialogue tells the story of thousands of homes of today’s era where young or middle-aged people are breaking the shackles of the traditional 9 to 5 job and choosing the path of ‘early retirement’. On one hand, with the help of technology and modern financial management, people are claiming to be financially independent between the age of 40 to 50, on the other hand, it is very difficult for the old and traditional values of the parents to digest this. For them, ‘successful life’ means only a permanent government or corporate job and pension, not a life driven by mutual funds and stock market returns.
Nowadays, ‘FIRE’ i.e. ‘Financial Independence, Retire Early’ model is becoming increasingly popular among the youth in the corporate world and on social media. The main objective of this concept is that a person should save and invest so much at an early age that he does not have to depend on a job for survival. The backbone of this model is considered to be ‘Formula 25′ or ’25x rule’. According to this mathematics, any person has to estimate his total expenditure for the entire year and multiply that annual expenditure by 25. For example, if the annual expenditure of a family is Rs 6 lakh, its FIR number will be Rs 1.5 crore. When a strong corpus of this amount or more is accumulated, a person can leave his job and live a comfortable life with the help of investment returns.
When a person decides to retire at the age of 49, it is a long story of years of hard work, financial discipline and aggressive investing. Normal people are able to save 20 to 30 percent of their income, whereas people adopting the FIRE model save 50 to 70 percent of their total income and keep investing in schemes like stock market, mutual funds, index funds and PPF. Suppose a professional is saving a huge amount from his salary every month and his savings and investment figures reach lakhs, then with the power of compounding (compound interest) a fund worth crores is created in a few years. This is the reason that by the time they reach the age of 49, such people become so financially strong that they do not have to lend a helping hand to anyone for their basic needs.
Even if all this mathematics fits perfectly on calculators and Excel sheets and the bank balance testifies that a person can live comfortably without working all his life, but in the Indian family environment, the mental satisfaction of parents goes beyond these figures. For a mother, her son always remains a child and her worries about the security of his future never diminish. In the times of parents, the measure of financial security used to be a government job, assured pension and fixed deposit (FD), where a fixed amount was received every month. In contrast, the modern FIRE model hinges entirely on stock market fluctuations, inflation rates and safe withdrawal rates. This is the reason why when a son tells his mother that he has retired and will no longer work, the mother’s heart panics and she repeatedly insists that the son find a job.
As attractive and exciting as the FIRE formula sounds, financial experts believe that it also has some hidden risks that cannot be ignored. In today’s times, rising inflation, especially the rising cost of medical and healthcare services, can derail any retirement planning. Moreover, if a person retires at the age of 49, he will have to depend on the same fund to survive for the next 30 to 40 years. If there is a prolonged downturn in the stock market or portfolio returns are below expectations, the savings may be at risk of being wiped out prematurely. This is why many savvy financial planners recommend options like ‘Barista Fire’ or ‘Coast Fire’ instead of quitting the job completely, where one continues doing light work of one’s choice so as to maintain mental satisfaction and social engagement.