 look news india
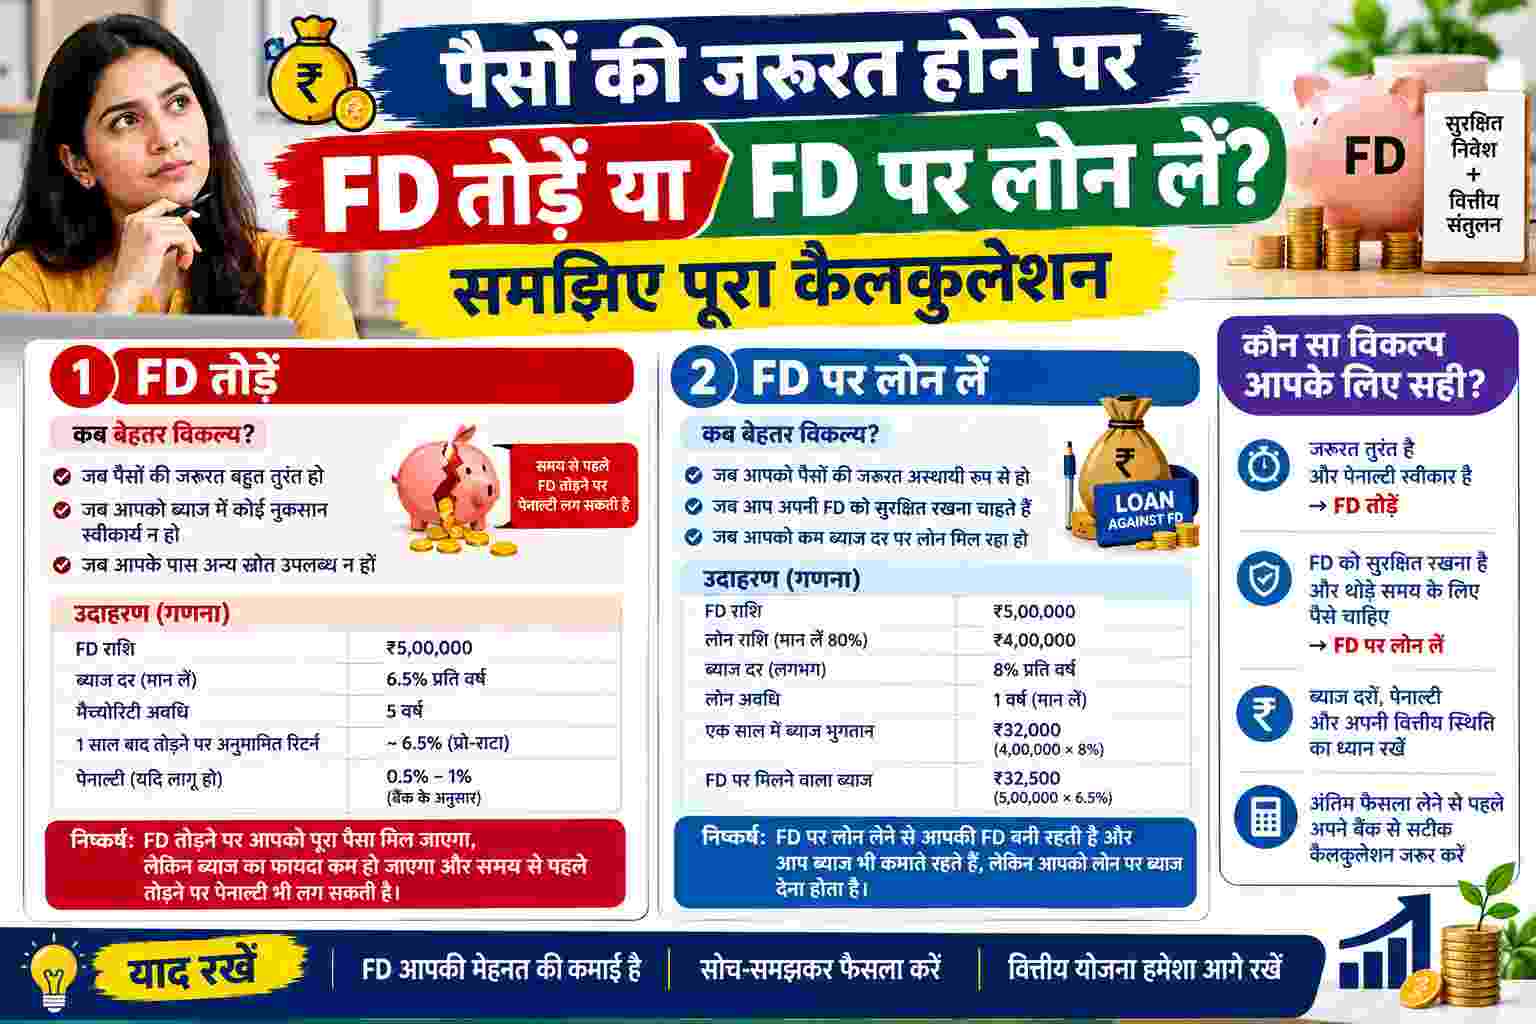
Many times in life, sudden emergency situations arise (Medical Emergency, urgent home repair or short-term cash crisis) when it becomes necessary to manage money immediately. At such a time, the first priority of most middle class investors is their bank deposits. Fixed Deposit (FD) leads to. But at that time, the biggest dilemma is whether the FD should be broken in the middle (Premature Withdrawal), or the same FD should be mortgaged and a loan should be taken from the bank (Loan Against FD / Overdraft)?
On the surface it seems that it is better to withdraw one’s own money rather than taking a loan, but this decision is not always correct in terms of banking rules and the mathematics of compound interest. Both options have their own financial implications, which are important to understand with numbers.
When you break an FD before maturity, the bank does not pay you interest at the rate at which the FD was booked. Here the investor faces double loss:
-
Penalty Clause (0.5% to 1%): Most banks (SBI, HDFC, ICICI, PNB) on pre-mature withdrawal Penalty of 0.50% to 1.00% Let’s cut.
-
Time Period Rule (Card Rate Adjustment): The bank does not give you the interest rate as per the original contract, but calculates the interest by deducting the penalty from the interest rate applicable at that time (Card Rate) for the period for which the FD has remained in the bank.
Understand the disadvantages with an example:
Suppose you ₹5,00,000 FD for 5 years 7.5% annual interest rate But it was done.
After 2 years you suddenly needed ₹2,00,000 and you broke the entire FD.
-
The bank will see what was the then rate of 2 year FD (let’s say 6.5%).
-
From this the bank will deduct a penalty of 1%, meaning you will only 5.5% You will get interest of Rs.
-
Result: You got only 5.5% interest instead of 7.5% on the last 2 years, and the 7.5% that was supposed to be compounded for the coming 3 years is lost forever.
Taking a loan against fixed deposit is actually a secured loan or overdraft facility:
-
Loan limit: The bank will credit your total FD value (principal + accumulated interest) 90% to 95% Get instant approval in the form of loan or credit limit. On an FD of ₹5 lakh, you can get a credit limit of up to ₹4.5 lakh.
-
Interest Rate (FD Rate + 1% to 2%): Usually the interest received on FD 1% to 2% additional interest Is taken on loan. If your FD is at 7.5%, then the loan will be available at 8.5% to 9.5%.
-
Interest only on amount utilized: If your sanctioned limit is ₹4 lakh and you have withdrawn only ₹1 lakh, then interest will be deducted only on that ₹1 lakh and only for the number of days for which the money has been used.
-
Zero processing fees and no CIBIL check: Since your FD is already secured with the bank, there are no processing fees, pre-payment charges or cumbersome income verification.
| financial standards | Breaking FD | Loan Against FD |
| original FD status | FD gets exhausted completely | FD continues to run and earn 7.5% interest |
| deduction/charge | A penalty of 0.5% to 1% is deducted from the interest. | No processing or pre-payment penalty |
| effective interest cost | full compounding future loss | Net cost difference of only 1% – 2% |
| repayment pressure | No repayment (the money was yours) | Flexible Repayment (Interest Monthly, Principal Anytime) |
| Tax Benefits (if 5-year 80C FD) | Cannot be plucked before 5 years | Loan is not available against tax-saving FD |
Suppose your FD of ₹5,00,000 is running at 7.5% and you need ₹2,00,000 for 6 months:
-
If FD breaks:
The entire FD of ₹5 lakh will be broken. The interest rate will be reduced from 7.5% to 5.5%. Interest loss of past period and compounding of next 3 years, total loss due to breakdown is approx. ₹35,000 to ₹50,000 Sits around.
-
If taking loan for 6 months:
Your FD will continue to earn 7.5% interest (earning around ₹18,750 on ₹5 lakh in 6 months).
Loan will be available at 8.5%. Interest on ₹2 lakh for 6 months is approx. ₹8,500 will be.
net result: Your FD earnings continued and you paid only ₹8,500 interest. You directly saved thousands of rupees.
When to choose Loan Against FD?
-
Short-term needs (1 to 12 months): If you know that you are going to get bonus, salary or any other fund in the next 3, 6 or 12 months from which you will repay the loan.
-
The total amount of FD needs to be less than: If the FD is of ₹5 lakh and the requirement is only ₹1 or ₹2 lakh.
-
Maturity is near: If the FD has only a few months left in its maturity, breaking it will result in huge losses; In such a situation, taking a loan is the wisest step.
When is breaking FD right?
-
Long term or indefinite time: If you do not have a fixed means to repay the loan for the next 2-3 years, the interest burden will exceed the FD returns if you keep the loan open for a long time.
-
Full amount required: If your FD is of ₹2 lakh and you need only the entire ₹2 lakh.
Therefore, whenever there is an urgent need of money, instead of closing the FD immediately, assess your repayment capacity. If the need is for a few months, taking an FD loan at a net 1-2% cost always protects your capital and compounding.