 look news india

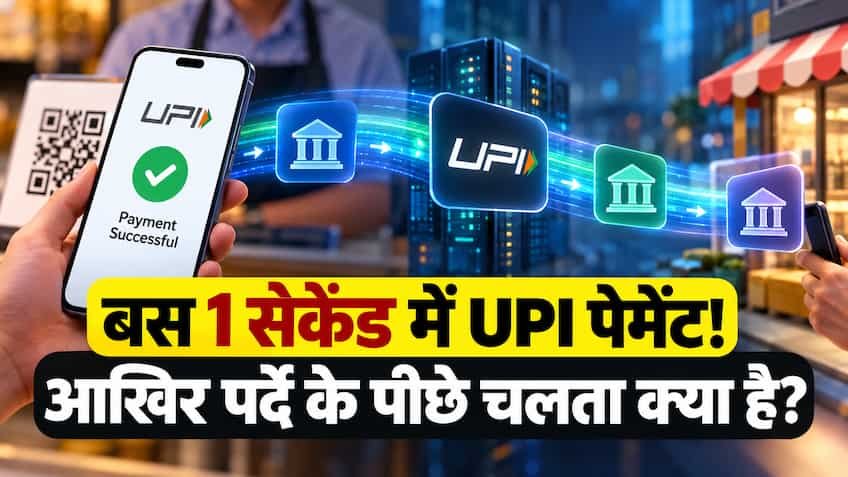
Bought the item at the shop, took out the phone, scanned the QR code, entered the 4 or 6 digit UPI PIN and a green tick appeared on the screen – ‘Payment successful’. This entire process takes only two to three seconds. For the consumer, it seems like a simple and magical experience, but behind the scenes of this simple looking interface, there is a very complex, secure and multi-layered financial network at work.
When you submit your PIN, your money doesn’t fly into the air and go straight to the other person’s phone. Rather, during this time your request passes through the country’s most secure banking network, the switches of National Payments Corporation of India (NPCI), the settlement rules of the Reserve Bank and the Core Banking System (CBS) of both the respective banks. Let us understand through which stages the journey of data and money goes through in the backend.
When you scan a shop’s QR code from Google Pay, PhonePe, Paytm or any other UPI app, the camera does not just take an image of the black-and-white dots but reads the unique ‘string’ hidden in it.
Each UPI QR code contains the merchant’s virtual payment address (VPA/UPI ID), merchant name, merchant category code (MCC) and the bank’s IFSC code in encrypted form. As soon as this code is decoded, your app immediately understands which person or merchant the payment is to go to. When you enter the amount and click on ‘Pay’, the actual cycle of transaction begins.
The keypad that opens on your screen when you enter the UPI PIN is not of your payment app (like PhonePe or GPay), but of NPCI’s Secure Software Development Kit (Common Library – CL). This means that your UPI PIN can neither be seen by your app nor saved on its server.
As soon as you enter the PIN:
-
The PIN is converted to a strong 256-bit encryption.
-
This encrypted data is immediately sent to NPCI’s central server.
-
NPCI sends it to your bank (Remitter Bank) for authentication.
-
Your bank verifies that the PIN is correct and that there is sufficient balance in the account.
Once the PIN is verified, your bank’s Core Banking System (CBS) gets activated.
-
The transaction amount is ‘debited’ from your account immediately.
-
Your bank’s server sends a digital confirmation to NPCI that ‘the money has been deducted’.
-
This phase is called ‘Debit Leg’ in technical language.
If during this time your bank’s server is down or the internet connection is broken, then often the money is deducted but does not move forward, which is later sent back to the account under the auto-reversal process.
NPCI’s Central UPI Switch is the heart and brain of this entire system. As soon as it receives the ‘Debit Successful’ signal from your bank, it immediately contacts the beneficiary bank where the shopkeeper’s account is maintained.
NPCI acts as a secure bridge (gateway) between the two banks. It instructs the shopkeeper’s bank in real-time to ‘credit’ the corresponding amount to the account of the concerned account holder.
As soon as the merchant’s bank receives the signal from NPCI, the amount is immediately added to the merchant’s account.
-
As soon as the credit is done, the shopkeeper’s bank sends a ‘success’ message to NPCI.
-
NPCI forwards this final status to your and the shopkeeper’s app.
-
A ‘Tick’ mark appears on your phone and ‘Payment received’ sounds from the shopkeeper’s soundbox.
This entire 5-step process is completed in 2 to 3 seconds using data packets traveling at the speed of light.
Here’s a very interesting technical fact that most people don’t know. The moment the payment appears successful on your phone, the money has not actually left your bank and been physically transferred to the merchant’s bank.
At the customer level it is immediately visible only as ‘Digital Ledger Entry’. Interbank settlement of real money between banks takes place in batches at fixed times during the day, managed by the clearing house of the Reserve Bank and NPCI.
After adding the accounts of millions of transactions throughout the day, NPCI calculates how much total money has to be paid to which bank (Net Settlement). After this, funds are transferred to the central accounts of banks through RBI. This dual system has been created to provide instant payment experience to the common consumer, making India’s UPI the most advanced and secure real-time payment system in the world.