 look news india
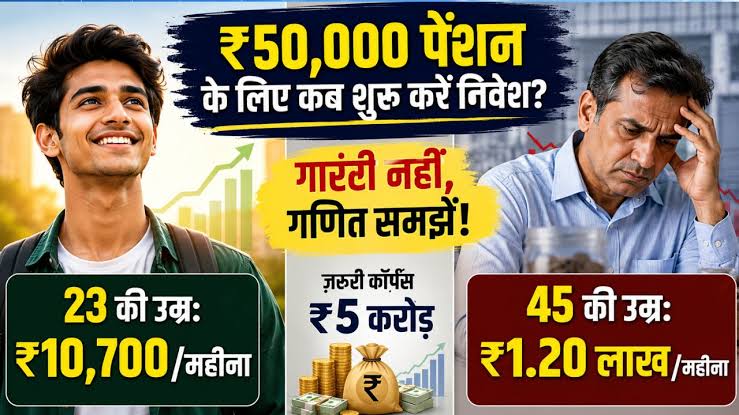
New Delhi/Mumbai/Lucknow (Business Desk): Every person dreams that when he retires from his job or business, he does not have to reach out to anyone for money in old age. In this era of rising inflation, whether you live in a metro city like Delhi-Mumbai or in a small town of Uttar Pradesh, Bihar, Rajasthan and Madhya Pradesh, after the age of 60, it is very important to have a regular income for household expenses and medicines. Often, employees and small businessmen working in the private sector worry about how their life will be after retirement, because they do not have the old pension facility like government employees. But do you know that there is such a wonderful and safe scheme of the Central Government, in which if you start investing at the right time, then after retirement you can get a guaranteed pension of Rs 50,000 every month? Yes, we are talking about ‘National Pension System’ i.e. NPS. In this scheme, not only do you get a huge pension every month, but on the day of retirement you also get a lump sum fund worth lakhs of rupees. Come, in today’s special report, let us understand in very simple language what is the complete mathematics of getting a pension of Rs 50 thousand per month.
What is National Pension System (NPS) and why is it safest to invest money in it?
The National Pension System (NPS) is a voluntary and long-term retirement savings scheme launched by the central government and regulated by the Pension Fund Regulatory and Development Authority (PFRDA). Earlier this scheme was only for government employees, but in the year 2009, the government opened it for every citizen of the country. Any Indian citizen between 18 years to 70 years of age (whether he is an employee, has his own business or is a housewife) can open his account in this scheme. The biggest feature of NPS is that it is a market-linked scheme, where your money is invested in equity (share market), corporate bonds and government securities. This is the reason why it gives much higher returns than PPF or Fixed Deposit (FD). If we look at the data of the last few years, NPS has given excellent annual returns to investors ranging from 10 percent to 12 percent on an average. Due to being under government supervision, there is no risk of your money being lost and in the long run, you get tremendous benefit of power of compounding.
What is the complete calculation (mathematics) to get a pension of Rs 50 thousand every month?
Now coming directly to the question that how much money will you have to invest from your pocket to get a pension of Rs 50,000 every month. Suppose your current age is 25 years and you start planning your retirement from this age. According to NPS rules, this scheme matures at the age of 60 years, which means you have a long time of 35 years to invest. If you start investing just Rs 5,000 (ie about Rs 166 per day) every month in NPS from the age of 25, then the total investment from your pocket in 35 years will be only Rs 21 lakh. Now, since this money is invested in the market and bonds, then if we assume an average annual return of 10 percent on it, then by the time you turn 60, your Rs 21 lakh will grow into a huge fund of about Rs 1 crore 91 lakh 41 thousand (about Rs 1.91 crore). In this, you will get direct profit of about Rs 1 crore 70 lakh only from interest.
You will get Rs 76 lakh in lump sum on retirement and pension for life.
When you retire at the age of 60 and Rs 1.91 crore is deposited in your NPS account, then the withdrawal rule of NPS will work. According to the rules, you can withdraw a maximum of 60 percent of your total fund in lump sum, which is completely tax-free, and it is mandatory for you to buy an annuity plan i.e. pension plan with at least 40 percent of the amount. But if your goal is to get a guaranteed pension of Rs 50,000 every month, then you will have to adopt a small smart trick. Instead of withdrawing 60 percent of your total corpus (Rs 1.91 crore), withdraw 40 percent in lump sum and put the remaining 60 percent in annuity (pension fund). According to this mathematics, as 40 percent, you will get about Rs 76 lakh 56 thousand in cash in your bank account on the day of retirement, through which you can fulfill your children’s dream of marriage, home or traveling the world. At the same time, when you buy an annuity plan with the remaining 60 percent share i.e. about Rs 1 crore 14 lakh 85 thousand and if you get an average annual return of 6 percent on it, then you will continue to get a guaranteed pension of about Rs 57,400 (ie more than Rs 50 thousand) every month for life.
If your age is 30 or 35 years then how much will you have to invest?
This question comes in the mind of many people that if their age is more than 25 years, then how can they get a pension of Rs 50 thousand. Its simple rule is that the later you start investing, the more you will have to increase your installment (SIP) amount every month. For example, if you are 30 years old and have 30 years left for retirement, then to get a monthly pension of Rs 50 thousand and a lump sum fund of around Rs 1.13 crore, you will have to invest between Rs 8,500 to Rs 10,000 every month. Whereas, if you start this plan at the age of 35, you will have to invest around Rs 15,000 every month for the next 25 years. What I mean to say is that time is the greatest asset in NPS; The earlier you start, the less burden on your pocket and the bigger the returns.
Two types of accounts are available in NPS and the benefit of bumper tax exemption.
Citizens investing in the National Pension System get the facility to open two types of accounts: first Tier-1 account and second Tier-2 account. Tier-1 is a mandatory retirement account, in which you can partially withdraw the deposited money before the age of 60 years only in special circumstances (such as serious illness, higher education of children or construction of a house). Whereas, Tier-2 account is like a normal savings account, which can be opened only by those who already have a Tier-1 account; You can withdraw money from this whenever you want. Apart from this, NPS is considered to be the best scheme in the country in terms of tax saving. By investing in it under the old tax regime, you get a rebate of up to Rs 1.5 lakh under Section 80C of Income Tax. Additionally, you get a separate tax exemption of Rs 50,000 under Section 80CCD(1B). That means you can save direct tax on total investment up to Rs 2 lakh in a financial year. Also, the government does not charge a single rupee tax from you even on 60 percent of the lump sum amount received on maturity.
How to open your NPS account online or in the nearest bank sitting at home
If you also want to secure your old age and have decided to start investing in NPS, then the process of opening an account is very easy. You can open your account through both offline and online methods. For the offline method, you can go to any big government or private bank (like SBI, PNB, HDFC, ICICI etc.) or the nearest post office (Point of Presence – PoP) of your city or town and fill the form along with KYC documents (Aadhaar card, PAN card and bank passbook). At the same time, if you want to open an online account sitting at home, then you will have to go to the official website of ‘eNPS’ (enps.nsdl.com or the portals of Gurgaon/Mumbai based Kfintech and CAMS). Register there with the help of your Aadhaar number and PAN card, verify the OTP received on mobile and open your account with just Rs 500 or Rs 1000 through online payment (Net Banking or UPI). As soon as the account is opened, you will get a 12 digit ‘PRAN’ (Permanent Retirement Account Number), which will be useful to you throughout your life.