 look news india
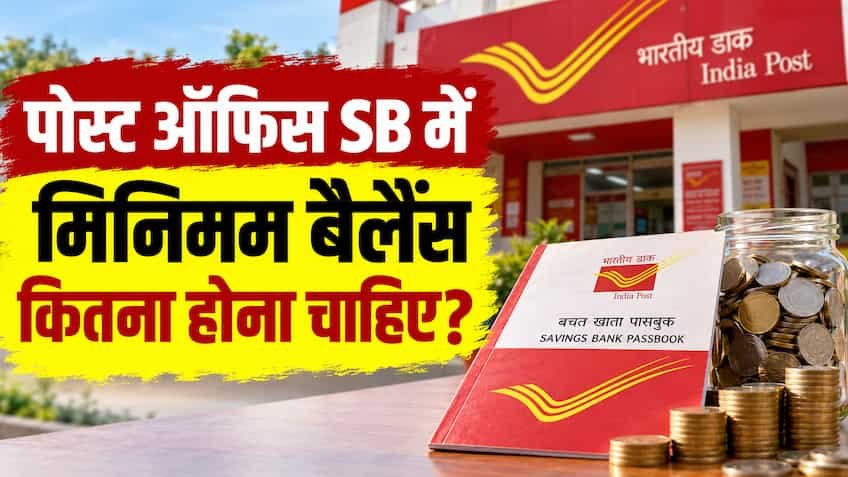
Whenever it comes to safe investment and reliable banking in India, the name of post office savings schemes first comes to mind. Crores of common citizens, senior citizens, families in rural and town areas of the country unwaveringly trust the Post Office Savings Account (POSA) to keep their hard-earned money completely risk-free. Government protection, attractive interest and a strong network of more than 1.5 lakh post office branches spread across the length and breadth of the country make it the common man’s bank. But do you know that to keep this popular post office savings account running smoothly, it is legally required to maintain a mandatory minimum balance? If this fixed amount is not maintained in your post office savings account, then the postal department not only imposes penalty and maintenance charges on your account, but after a certain limit your account may also be automatically closed forever.
It is often seen that after opening an account in the post office, people get the interest transferred from other small savings schemes like National Savings Certificate (NSC), Kisan Vikas Patra (KVP), Senior Citizen Savings Scheme (SCSS) or Recurring Deposit (RD), but forget to pay attention to the daily balance of the original savings account. The Department of Posts has made the rules related to minimum balance and penalty quite strict and transparent to prevent financial indiscipline of account holders and to balance the operating expenses of digital banking infrastructure. If you also have a post office savings account, then you should understand well that it is mandatory to have a minimum amount of money in the account at all times and how much money will be deducted from your pocket if the balance decreases.
As per the current National Savings Account rules of the Department of Posts, the minimum balance requirement in any individual or joint post office savings account is: ₹500 Has been decided. When you go to any post office branch to open a new savings account, you still need to deposit a minimum of ₹500 as the first deposit through cash or cheque, to activate the account.
In earlier times, when check book facility was not available, the Postal Department used to allow maintaining a minimum balance of ₹ 50 for non-cheque facility accounts. But now after complete digitization of the banking system and implementation of Core Banking Solutions (CBS), a uniform rule of ₹500 has been implemented for all types of post office savings accounts, whether you have a check book facility or not. This simply means that the account holder should not let his account balance go below ₹500 under any circumstances. If you are going to withdraw money from an ATM or post office window, the system will not allow you to make any withdrawal that leaves the account balance below ₹500.
If for some reason or due to a technical transaction the balance of your post office savings account slips below ₹500 during the financial year, the Department of Posts imposes a financial penalty on the account holder, which is officially Account Maintenance Fee It is said.
Under the clear rules of the Postal Department, this penalty is not deducted every month, but on the last working day of the financial year i.e. 31st March is deducted from the account. If the balance recorded in the account as on 31st March is found to be less than ₹ 500, then the postal department will withdraw the amount directly from the account. ₹50 (including GST) Deducts Rs as maintenance charge. This charge of ₹50 will be deducted continuously at the end of every financial year until the account balance reaches ₹500 or more. Many account holders are under the misconception that like commercial banks, a huge penalty of Rs 200 to Rs 500 will be deducted every month, but the postal department charges only a nominal fee of Rs 50, although the consequences of ignoring it can be huge.
Apart from the penalty deduction, the biggest and most obvious disadvantage of reducing the minimum balance is that your account is completely deprived of the attractive interest received during that period. Presently on Post Office Savings Account by the Government of India 4.0% per annum Guaranteed interest is given at the rate of Rs. 1000/- which is calculated on monthly basis and credited to the account at the end of the financial year.
According to the interest calculation rules of the post office, the interest is determined on the monthly basis. From 10th to last day of the month This is done on the basis of the minimum balance present in the account between Rs. If your account balance goes below ₹500 on any day between the 10th of the month and the last day of that month, the Postal Department will not give you a single paisa interest for that entire month. For example, if you have ₹50,000 in your account for 29 days of the month, but on one day the balance drops to ₹400 on the 12th, you will get zero interest for that entire month. Therefore, it is very important to always maintain an amount of more than ₹ 500 in the account to avail regular benefits of interest.
The most serious consequence of the process of deducting account maintenance fees comes in the form of permanent closure of the account. Suppose an account holder has only ₹ 40 or ₹ 50 left in his post office savings account and he has not deposited any new money in it for a long time. As soon as March 31 of the financial year comes, the postal department will deduct a maintenance charge of ₹50 under the system.
If the account balance decreases as soon as this ₹ 50 charge is deducted, Zero (₹0) If it is done, the CBS software of the postal department will update that account. Automatically & Permanently Closed Does. Once the account is automatically closed by the system due to zero balance, it cannot be reactivated. In such a situation, the account holder will have to open a completely new savings account by submitting fresh KYC documents to conduct post office transactions in future. Therefore, to keep your old and active account safe, it is the most sensible step to deposit additional amount in it in time.
Post Office Savings Account may come with a strict requirement of minimum balance of ₹500, but its benefits are no less than any big government or private bank. The account holder gets complete freedom to transfer money through mobile banking, UPI and online NEFT/RTGS from the comfort of home by linking his account with India Post Payments Bank (IPPB). Apart from this, cash withdrawal can be done from the ATM of any bank across the country using the post office ATM card. Under Section 80TTA of the Income Tax Act, full tax exemption is also available on annual interest received from savings account up to ₹ 10,000.
If for some reason your account has been lying without transactions for a long time and its balance has reached below ₹500, then immediately go to your nearest Sub-Post Office (SO) or Head Post Office (HO). Fill the pay-in-slip there and deposit the required amount in the account so that the balance reaches at least ₹ 1,000 or more. With this, you will not only be saved from the penalty of ₹ 50 which will be deducted on March 31, but the regular interest at the rate of 4% will also be safe and your account will never be closed. Post Office savings schemes are a symbol of security, all you need to do is follow their minimum balance rules to keep your financial health in good shape.