 look news india
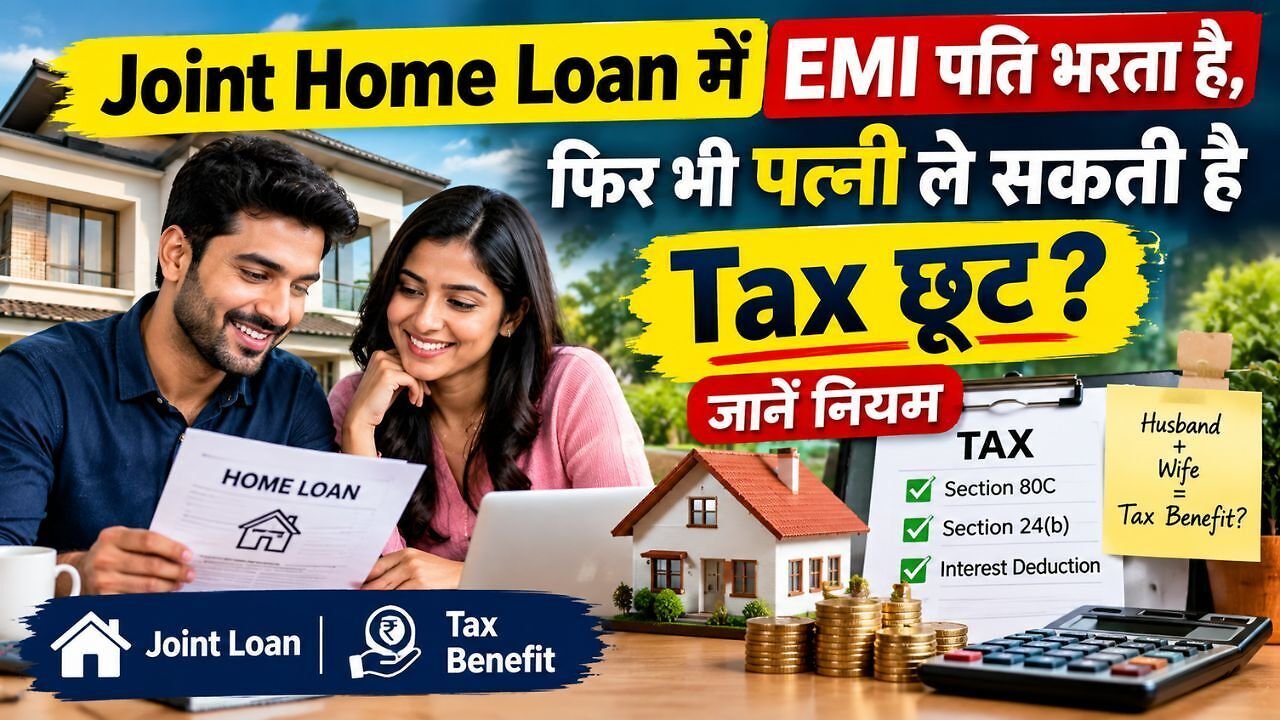
When a middle-class family takes a home loan from a bank to buy a house, usually the names of both husband and wife are included in the house registry and the loan document. The most discussed question among working couples in big cities like Lucknow, Noida, Ghaziabad, Kanpur, Delhi and Mumbai is that if the husband is paying the entire monthly home loan EMI from his bank account, then can the wife also claim tax benefit on that home loan in her Income Tax Return (ITR). The simple, clear and legal answer to this question is that as per income tax rules, if the wife has zero financial contribution towards the EMI payment, then she cannot claim any kind of tax exemption on the home loan. Under the Income Tax Act, tax exemption is not available merely on the basis of relationship or name only on paper, but it is mandatory to prove the actual payment of EMI financially. Many times, in a hurry to save tax, taxpayers show deductions in both the files, which can lead to scrutiny notices and heavy fines from the Income Tax Department in future.
As per the established provisions of the Income Tax Department, three basic criteria are legally required to be fulfilled to avail tax exemption under Section 24(b) and Section 80C on home loan. If even one of these conditions remains unfulfilled, the tax exemption claim is declared invalid.
-
1. Legal co-owner of the property: It is mandatory to register the wife’s name as a co-owner in the sale deed and registry of the house or flat. If the property is registered in the husband’s name only, the wife cannot be eligible for tax exemption in any case, even if the loan is joint.
-
2. Co-borrower in loan: The wife’s name should be mentioned as a co-applicant or co-borrower in the loan agreement of the bank or housing finance company.
-
3. Actual Payment of EMI (Actual Financial Contribution): The most important and decisive condition is from whose account the monthly loan installment is actually being paid. If the husband is paying 100% EMI from his salary account and no money is being deducted from the wife’s account, then 100% tax deduction will be available only to the husband, not even 1% benefit can be given to the wife.
Often people assume that if the bank has made the wife a co-borrower to increase loan eligibility and her name is also included in the registry, then she is automatically entitled to tax benefits. Financial experts and Chartered Accountants (CAs) say that being a co-owner and co-borrower is the first step to avail tax benefits, but it is not the last step. Section 24(b) of the Income Tax Act clearly states that exemption on interest will be given only to the person who has borne the actual burden of that interest. If the wife is working and falls in the tax slab, but does not transfer even a single rupee of EMI from her bank account, then her financial contribution will be considered zero in the eyes of the Income Tax Department. If she shows this deduction in her ITR, the Assessing Officer may reject the claim by asking for the bank statement and may consider it as a fraudulent deduction and may charge interest and penalty.
If both husband and wife are working and both want to save tax, by adopting a well-planned financial strategy they can avail exemption on the total taxable income of up to ₹7 lakh every year at the family level. For this some practical steps need to be taken:
-
Decide EMI ratio: Both husband and wife should decide on a fixed proportion of EMI and pay from their respective bank accounts. For example, a ratio of 50:50, 60:40 or 70:30 can be kept.
-
Correct use of joint account: If the EMI is being deducted from a joint bank account, then both the spouses should transfer the money from their individual salary accounts to that joint account in the fixed proportion, so that the contribution of both is clearly visible in the bank statement.
-
Mathematics of Ownership and Deduction (in old tax system): When both pay EMIs, the husband can claim exemption on home loan interest up to ₹ 2 lakh and the wife can also claim exemption up to ₹ 2 lakh separately (total ₹ 4 lakh) under Section 24(b). Under Section 80C, husband can take deduction of ₹ 1.50 lakh and wife can also take deduction of ₹ 1.50 lakh (total ₹ 3 lakh) on Principal Repayment. In this way both together can avail double benefit of deduction up to ₹ 7 lakh.
While doing tax planning on home loan, it is very important to keep in mind which tax regime of income tax you are choosing. At present the new tax regime implemented by the Central Government is the default system. Under the new tax regime, tax deductions for both interest (Section 24B) and principal (Section 80C) on home loans for self-occupied property (a house in which you are living yourself) have been abolished. This double tax exemption of interest and principal on home loan is available only to the taxpayers choosing the old tax regime. Therefore, before filing ITR, both husband and wife should do a comparative study of their tax slabs and deductions. If the wife is non-working or her income is below the basic exemption limit, the husband should pay the entire EMI in his own name and avail the full deduction of maximum ₹3.5 lakh (₹2 lakh interest + ₹1.5 lakh principal) in his own file under the old tax regime.