 look news india

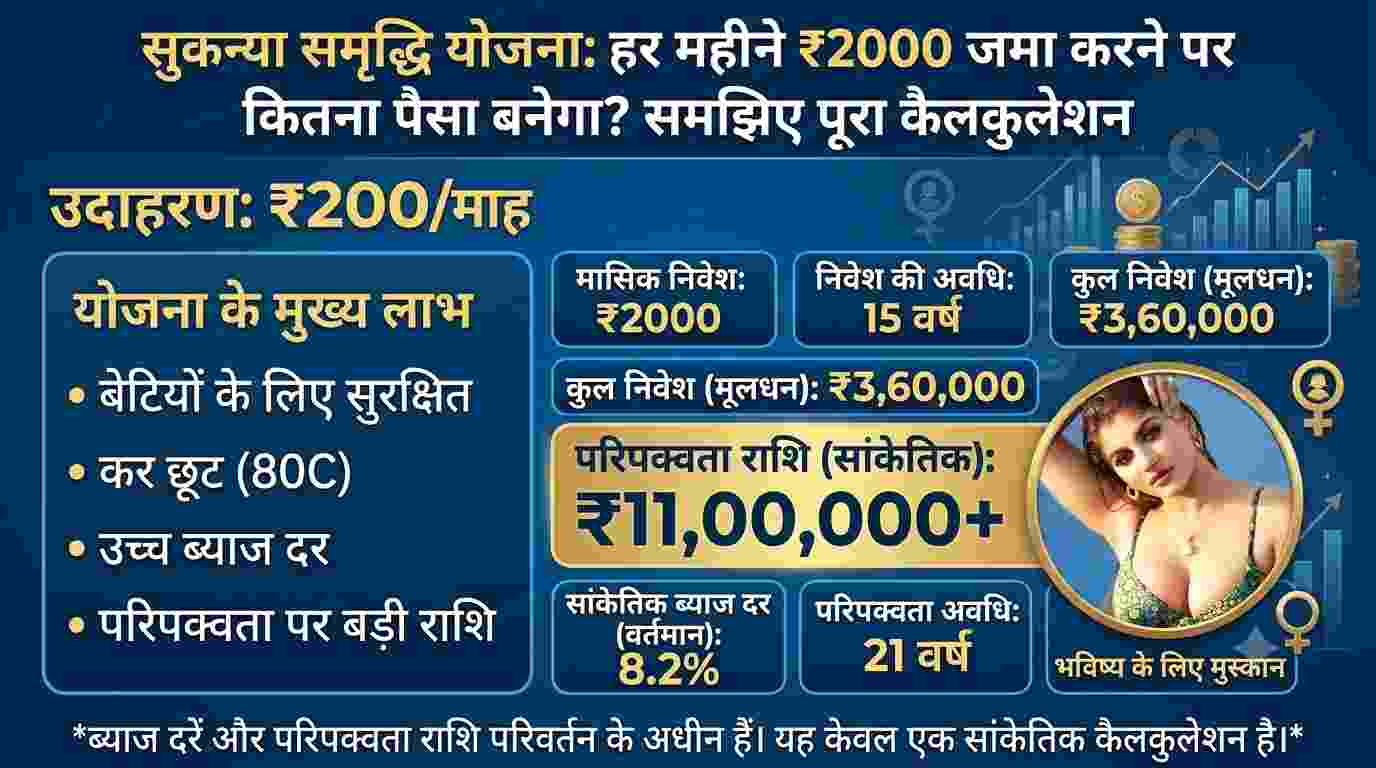
To create a safe and guaranteed fund for your daughter’s higher education and major wedding expenses, the Central Government’s ‘Sukanya Samriddhi Yojana’ (SSY) is the most popular and trusted savings scheme in the country. Currently the government is offering 8.2 percent compounded annual interest on this scheme, which is the highest compared to any government small savings scheme or bank FD. Many parents want to know that if they deposit a small amount i.e. only ₹2,000 every month in their daughter’s account, how much money will she get on maturity. Let us understand its complete and accurate calculation based on the rules of Sukanya Samriddhi Yojana and 8.2% interest rate.
The most special thing about Sukanya Samriddhi Yojana is its investment and maturity period rules. In this scheme, money has to be deposited only for 15 years from the date of account opening, whereas the account matures after a total of 21 years. That means, in the last 6 years from 15th year to 21st year, you do not have to deposit a single rupee from your pocket, but compound interest at the rate of 8.2% keeps getting added on the entire amount deposited in your account.
If you deposit ₹2,000 every month (i.e. ₹24,000 annually) into this account, the total calculation at the current interest rate of 8.2% will be as follows:
| Calculation Parameters (SSY Calculation) | Amount/Description (Based on 8.2% annual interest rate) |
| Monthly Deposit | ₹2,000 per month |
| Annual Deposit | ₹24,000 per year |
| Contribution Period | 15 years |
| Total investment from your pocket in 15 years | ₹3,60,000 (₹24,000 × 15 years) |
| Total Maturity Tenure of the account | 21 years |
| Total Interest Earned in 21 Years | ₹7,89,139 (approximately ₹7.89 lakh — completely tax-free) |
| Total maturity amount after 21 years | ₹11,49,139 (approximately ₹11.50 lakh) |
(Note: If you deposit ₹2,000 before the 5th of every month, you get the full benefit of interest from the same month, whereas returns may be slightly higher if you deposit ₹24,000 in lump sum annually.)
If you look at this calculation carefully, you will find that in 15 years you deposited a total of ₹ 3,60,000 from your pocket, but after completion of 21 years, you get back a total of ₹ 11,49,139. That means you get a net profit of ₹ 7,89,139 only in the form of interest, which is more than double your original investment. This happens because by the 15th year your deposit and interest add up to around ₹ 7.15 lakh. After this, 8.2% compound interest is charged on the same huge amount for the next 6 years (from 16th to 21st year) without any new investment, which adds up to an interest of more than ₹ 4.30 lakh in the last 6 years alone.
Sukanya Samriddhi Yojana comes under the EEE (Exempt-Exempt-Exempt) category under the Income Tax Act, which means it gets tax exemption at three levels. First, the amount deposited every year gets the benefit of tax deduction of up to ₹ 1.5 lakh under Section 80C under the old tax system. Second, there is no tax on the interest added to the account every year. Third, the entire maturity amount (₹11.49 lakh) received after 21 years is also completely tax-free. In this scheme, minimum ₹ 250 and maximum ₹ 1,50,000 (i.e. maximum ₹ 12,500 per month) can be deposited in a financial year.
Under this scheme, parents or legal guardians can open an account in any post office or authorized bank in the name of their daughter below 10 years of age. Two separate accounts can be opened for a maximum of two daughters in a family (exception applies in case of birth of twin or triple daughters). If money is required for the daughter’s higher education, up to 50 percent of the total balance at the end of the previous financial year can be withdrawn after the daughter completes 18 years of age or passes 10th class. Apart from this, the facility of premature closure of the account and withdrawal of the entire amount is also available on the occasion of daughter’s marriage after the age of 18 years.