 look news india
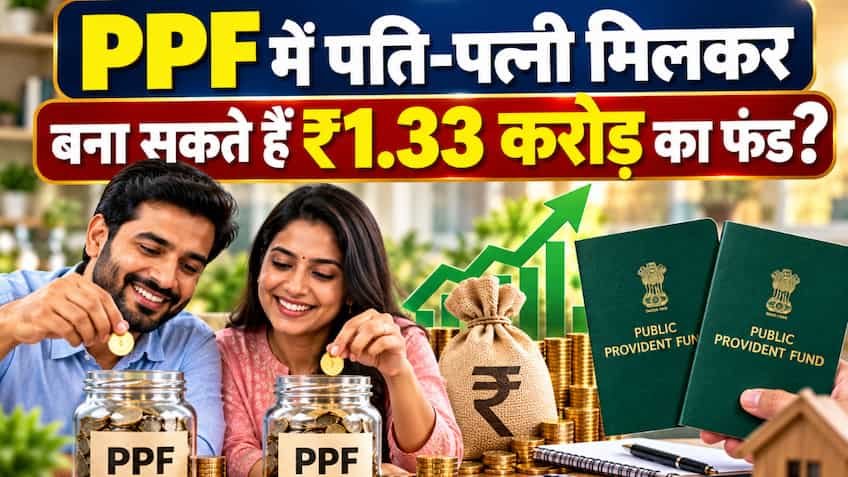
Public Provident Fund i.e. PPF is still the most reliable medium of 100% government guarantee and secure wealth creation for the middle class families and employed people of the country. People generally think that only a maximum of ₹1.5 lakh can be deposited in PPF in a financial year, which limits the fund limit in the long run. But if husband and wife come together to make a smart financial strategy and invest through two separate PPF accounts, a huge and completely tax-free fund of over Rs 1.33 crore can be created over a period of 20 years without any stock market risk.
Opening of joint PPF account is not allowed under the rules of Public Provident Fund Scheme (PPF Scheme, 2019). However, every adult citizen of the country can operate an independent PPF account on his/her individual PAN.
According to this rule:
-
Husband’s Independent Account: Maximum investment in a financial year is ₹1,50,000.
-
Wife’s Independent Account: Maximum investment in a financial year is ₹1,50,000.
-
Total annual investment of the family: The total savings from both the accounts combined would be ₹3,00,000 per year (i.e. combined savings of ₹25,000 per month).
Even if the wife is a homemaker and has no independent income, the husband can still transfer this amount from his income to the wife’s account as a gift. Despite the provisions of clubbing of income under Section 64 of the Income Tax Act, since the entire interest and maturity amount of PPF is completely tax-free under Section 10(11), no additional tax liability arises even in case of clubbing.
Currently on PPF by the government 7.1% annual interest rate Has been decided, which is compounded annually. The basic lock-in period of PPF is 15 years, but on completion of 15 years, there is a statutory facility to extend it in a block of 5 years (Extension with Contribution).
The detailed math of both the accounts over a period of 20 years (15 years basic + 5 years first extension) is as follows:
| Description (20 year period) | Husband’s PPF account | Wife’s PPF account | Total Joint Family Fund (Both Accounts) |
| Annual Deposit | ₹1,50,000 | ₹1,50,000 | ₹3,00,000/year |
| Total Deposit (Principal) in 20 Years | ₹30,00,000 | ₹30,00,000 | ₹60,00,000 |
| Total Interest Earned (Wealth Gain) at 7.1% | ₹36,58,288 | ₹36,58,288 | ₹73,16,576 |
| Total maturity amount after 20 years (Corpus) | ₹66,58,288 | ₹66,58,288 | ₹1,33,16,576 (~₹1.33 crore) |
Thus, the total capital accumulated by the family will be ₹60 lakh, while the total interest received on the basis of compounding will be more than ₹73.16 lakh.
Real wealth creation in PPF starts after the 15th year. When your account completes 15 years, an annual deposit of ₹1.5 lakh creates a corpus of approximately ₹40.68 lakh in one account (₹81.36 lakh in both accounts).
After this, when you extend the account for 5 years by filling Form H in the 15th year, the funds in both the accounts will directly jump from ₹ 81.36 lakh in the next 5 years. ₹1.33 crore reaches beyond. The main reason for this is that the interest received after the 15th year gets compounded on your previous huge base of ₹81 lakh.
PPF has ‘EEE’ (Exempt-Exempt-Exempt) status in the Indian tax system:
-
Rebate on investment: Under the old tax system, tax deduction of up to ₹ 1.5 lakh is available annually in Section 80C. If both are taxpayers, both can avail separate tax exemption of ₹1.5 lakh.
-
Zero tax on interest: The interest added to the account every year is completely tax-free.
-
Zero tax on withdrawals: After 20 years, when you withdraw the entire amount of ₹ 1.33 crore, there will be zero Capital Gains Tax or any other income tax on it.
-
Deposit before 5th of every month: As per PPF rules, interest is calculated on the minimum balance available between the 5th and last date of the month. Therefore, always transfer the monthly installment to the account between 1st and 5th.
-
Rule of April 5 on lump sum deposit: If you deposit ₹1.5 lakh together for the whole year, it can be withdrawn every year. 5th April Please submit before . By doing this, you get interest for full 12 months, which adds additional profit of lakhs of rupees to the maturity corpus at the end of 20 years.