 look news india
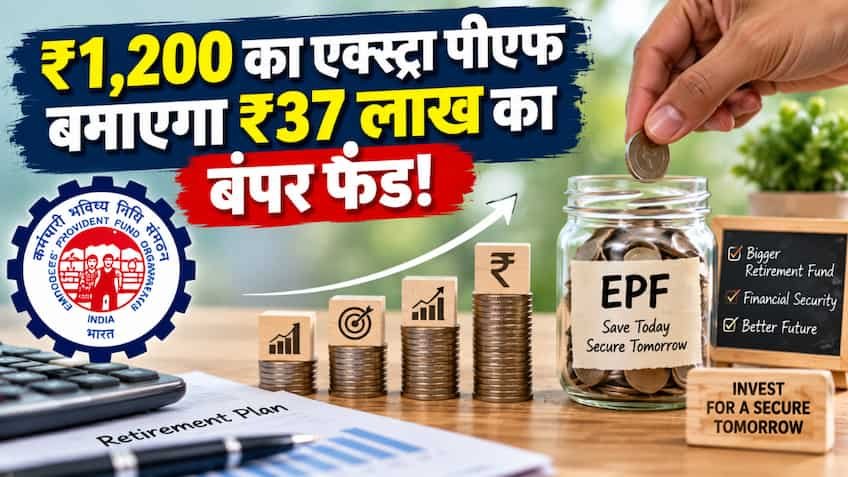
For employed employees, Employees’ Provident Fund Organization (EPFO) has been the most preferred means of safe and guaranteed returns for a long time. Most organized sector workers are limited to only mandatory contributions and assume that the amount they receive at the time of retirement will be sufficient for old age. The reality is that the ever-increasing pace of inflation is increasing future expenses manifold. A new estimate by financial analysts suggests that by adding an additional contribution of just ₹1,200 every month from your regular salary, you can directly add an additional corpus of over ₹37 lakh to your account at the time of retirement. This is the circular magic of small savings which it is in the interest of every salaried person to understand in time.
According to EPFO rules, at present 12 percent of the basic pay and dearness allowance (DA) for organized sector employees is deposited in the EPF account. Under the minimum mandatory limit, this contribution has been fixed at ₹1,800 per month on a basic salary of ₹15,000. An equal amount is also deposited by the company or employer, out of which a major portion goes to the Employees’ Pension Scheme (EPS) and the remaining to the EPF. Most of the employees maintain the contribution at this minimum level of ₹1,800 in the initial days of their service and never consider that a little extra contribution can change the entire picture of their future.
When an employee increases his monthly contribution to ₹3,000 instead of the mandatory ₹1,800, the extra amount out of his pocket is only ₹1,200 per month. This difference of ₹ 1,200 may seem like two-three cups of coffee or a simple breakfast outside in today’s daily life, but this small step in the provident fund account turns out to be a strong financial shield over the decades.
To understand this comparison clearly, let us take the example of a 25 to 30 year old young employee, who continues to contribute actively to the job for 30 years of his career. Let us assume that the current annual interest rate offered by EPFO remains stable around 8.25 percent and the employee deposits his contribution regularly every month.
In Case 1, if the employee deposits only the minimum mandatory ₹1,800 per month, his total principal deposited over 30 years is approximately ₹6,48,000. With a compound interest rate of 8.25 percent, the total maturity corpus formed on this amount after 30 years comes to approximately between ₹27.6 lakh to ₹28 lakh. This amount may seem fine for general needs, but compared to inflation after thirty years, it is no longer very big.
In Case 2, if the same employee increases his share of contribution to ₹3,000 per month, i.e. ₹1,200 more than before, the total principal deposited by him in 30 years will be ₹10,80,000. On this ₹3,000 monthly investment, at the same 8.25 per cent compounding rate, the total corpus created at retirement amounts to more than ₹65 lakh.
Now look at the difference between the two results. With ₹1,800 the retirement fund was around ₹28 lakh, while with ₹3,000 it works out to be around ₹65 lakh. The direct difference between the two works out to be around ₹37 lakh to ₹37.5 lakh. You deposited just ₹4,32,000 from your own pocket over 30 years (i.e. ₹1,200 times 360 months), and in return your account got added to an additional ₹37 lakh. This is the real power of compounding, where over time the interest received on interest becomes many times larger than the principal amount.
The question that arises in the minds of many employees is how they can increase their monthly contribution from ₹1,800 to ₹3,000 or more. For this, EPFO has given a very simple and transparent option of Voluntary Provident Fund (VPF). Under VPF, any employee can request the HR or Payroll department of his company to voluntarily deposit up to 100 percent of his basic and DA in the EPF account.
The amount deposited in VPF also gets the same interest which is decided by the government on the normal EPF account. This does not require any new account or separate process, rather it is directly linked to your existing Universal Account Number (UAN). If your employer is deducting only ₹ 1,800 from your basic salary, then you can start VPF of ₹ 1,200 by filling a simple form. This will instantly bring your total monthly contribution to ₹3,000.
One of the biggest attractions of additional investment in EPFO is its security and tax efficiency. Unlike the stock market or mutual funds, there is no risk of market fluctuations. Being backed by the Government of India, it has 100% guarantee on both principal and interest.
Under Section 80C of the Income Tax Act, an annual tax exemption of up to ₹1.5 lakh is available on the amount deposited in EPF and VPF. Additionally, interest on total employee contributions up to ₹2.5 lakh in a financial year remains completely tax-free. If you deposit ₹3,000 every month, your total contribution over the year is only ₹36,000, which is well within the tax-free limit of ₹2.5 lakh. This means that you will not have to pay any tax on the additional profit of ₹37 lakh and the entire maturity amount will come directly into your hands.
This mathematics of compounding works to its full potential only when you give it enough time. If an employee starts this extra ₹1,200 at the age of 40 or 45, he will get only 15-20 years and will not be able to reach the difference of ₹37 lakh. Young people who are starting their career at the age of 22 to 28 years have a long time of 30 to 35 years. At the beginning of your career, the extra burden of ₹ 1,200 does not feel at all on the budget, but at the age of retirement, this small decision makes you more financially independent and stress-free than others.
It takes just ten minutes to contact your company’s HR to opt for VPF or get your EPF contribution revised. Instead of postponing retirement planning until tomorrow, making this small difference of ₹1,200 a habit today will prove to be the smartest financial decision for your future.