 look news india
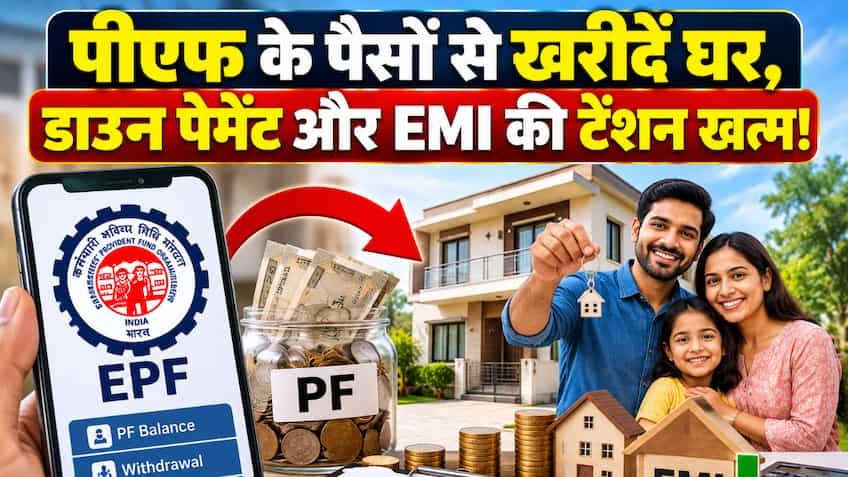
Buying a dream home is the biggest dream of every working person. But due to the skyrocketing prices of real estate in metro cities and rapidly developing Tier-II cities, the biggest challenge comes in arranging the down payment in one lump sum and paying the huge home loan EMI every month. Often people make the mistake of taking expensive personal loans or borrowing from relatives to bridge the 10 to 20 percent gap between their pocket budget and the bank loan. Very few employees know that the Employees Provident Fund Organization (EPFO) gives its members the legal facility to withdraw up to 90% of the funds from the PF account to buy a house, book a flat, buy a plot, get a house constructed and even pay the monthly installments of home loan taken from the bank.
Under the Employees Provident Fund Scheme 1952 (EPF Scheme), the provisions related to housing have been made extremely flexible and employee-friendly. Specific provisions of EPFO like Para 68BD And Para 68BB Under this, employees can use this fund only during their service. There is no need to leave the job for this, rather it is a non-refundable advance, which you do not have to return to the PF account again in future. If you are also planning to buy a new house or flat, then know how you can use your PF balance strategically.
EPFO has notified a special housing scheme (EPFO Housing Scheme) to fulfill the dream of employees of owning their own house, which can be availed under the EPF scheme. Para 68BD Is operated under. The biggest attraction of this scheme is that under this, the member can get maximum amount of the total amount deposited in his PF account (sum of employee and employer’s share including interest). up to 90% Can withdraw lump sum.
To avail this 90% withdrawal facility, it is mandatory for the employee to fulfill the following basic conditions:
-
Minimum service period: The total EPF membership period of the member whether consecutively or across different companies is at least 3 years There should be.
-
To be a member of a housing society: This withdrawal is primarily available for purchasing a flat/house directly from a registered housing society, government housing board (like DDA, MHADA, Housing Development), or builder/promoter, where at least 10 members are registered as a group or society.
-
Minimum balance requirement: At the time of application the member’s EPF account (or joint PF account of both spouses) has at least ₹20,000 It is mandatory to have a balance.
-
Only once in a lifetime: This special benefit of 90% withdrawal is given to the member only once in his entire working life.
If you are purchasing independent land as an individual instead of a registered society or want to build a house on your ancestral plot, then you can avail the EPF scheme for this. Para 68B And Para 68BB Withdrawal arrangements have been made under:
-
To buy a residential plot: For this the member must have completed at least 5 years of service. In this, withdrawal equal to 24 months basic salary (Basic + DA) of the member or the actual cost, or the total balance in the account (whichever is less) is available.
-
To buy a ready-to-move house or flat: After 5 years of continuous service, the member can withdraw his 36 months’ basic salary and DA or the total PF balance, whichever is less.
-
For house construction: If the land is already in your or your wife’s name, then you can get an advance amount equal to 36 months’ basic + DA for building a house.
-
Home Repairs/Additions: After 5 years of construction or purchase of the house, an amount equal to 12 months’ basic salary can be withdrawn for its renovation or expansion (additional withdrawal option is also available for the second time after 10 years).
EPFO is not just limited to giving down payment, but it also provides a revolutionary solution for those whose monthly salary accounts for a large part of home loan EMIs. Under Para 68BD, members can give a Standing Instruction to EPFO.
Under this arrangement, EPFO will auto-transfer the fixed EMI amount every month from your PF account directly to your bank or housing finance company (like SBI, HDFC, LIC HFL etc.). As long as there are sufficient funds in your account, your EMIs will be paid on time and you will not have to deduct any money separately from your salary. This facility proves to be a boon for those employees who are taking a career break for some reason, changing jobs or who have experienced a temporary slowdown in their monthly income.
| purpose of withdrawal | Applicable rules/paragraphs | minimum essential service | maximum withdrawal limit |
| Flat/House Purchase (Housing Scheme) | Para 68BD | 3 years | Of total PF fund (employee + employer) up to 90% |
| Purchase of vacant residential plot | Para 68B | 5 year | 24 months (Basic + DA) or actual cost |
| House/Flat Purchase (Individual) | Para 68B | 5 year | 36 months (Basic + DA) or Total Accumulated Fund |
| House construction (on own plot) | Para 68B | 5 year | 36 months (Basic + DA) or construction cost |
| Home Loan Prepayment / EMI Payment | Para 68BB | 3 to 5 years | Accumulated Fund/36 months salary (subject to rules) |
| House Renovation/Repair | Para 68B | 5 years (after construction of house) | 12 months of (Basic + DA) |
Now there is no need to go to EPFO office by filling paper forms to withdraw advance from PF. The entire process is 100% digital from the Member Services Portal:
-
Login to Unified Portal: First of all go to the official member portal of EPFO (unifiedportal-mem.epfindia.gov.in). Login by entering your 12 digit UAN number, password and captcha.
-
Check KYC Details: Make sure that your Aadhar Card, PAN Card and bank account details are ‘Verified’ on the portal and the bank account name and UAN name match letter-by-letter.
-
Select Online Claim Menu: in the menu above ‘Online Services’ Go to and from the drop-down ‘Claim (Form-31, 19, 10C & 10D)’ Click on.
-
Verify Bank Account and Select Form 31: ‘Verify’ by entering the last 4 digits of your registered bank account. After this click on ‘Proceed for Online Claim’ and select ‘I want to apply for’ ‘PF Advance (Form 31)’ Select.
-
Purpose and Document Upload: In ‘Purpose of Advance’ select ‘Purchase of House/Flat/Construction’ or ‘Housing Loan Repayment’. Fill the required amount, enter your current address and upload the scanned copy of bank passbook or canceled check (100 KB to 500 KB, clearly readable). Enter the OTP received on Aadhaar linked mobile and submit it. The money is credited directly to your bank account, usually within 7 to 10 working days.
Although withdrawing money for home from EPF solves the immediate financial crisis, according to financial planners this step should be taken only after careful consideration:
-
Disadvantages of Retirement Fund: Guaranteed and compounded interest of 8.25% or more is available on EPF, which is completely tax-free. If you withdraw Rs 10-15 lakh from your PF at the age of 30 or 35, your potential corpus of crores of rupees may reduce due to the effect of compounding at the time of retirement.
-
Tax Free Withdrawal: If you have completed 5 years of continuous service, PF advance withdrawn for housing under Section 10(12) of the Income Tax Act completely tax-free It happens. No TDS is deducted on this.
-
Set priority: If you are easily getting a home loan from the bank at a normal interest rate of 8.5% to 9% and are getting the benefit of tax deduction (Section 24b and Section 80C), then withdraw PF only to the extent of meeting the shortfall of down payment; Avoid draining the entire 90% of the fund so that your future pension and retirement security remains intact.