 look news india
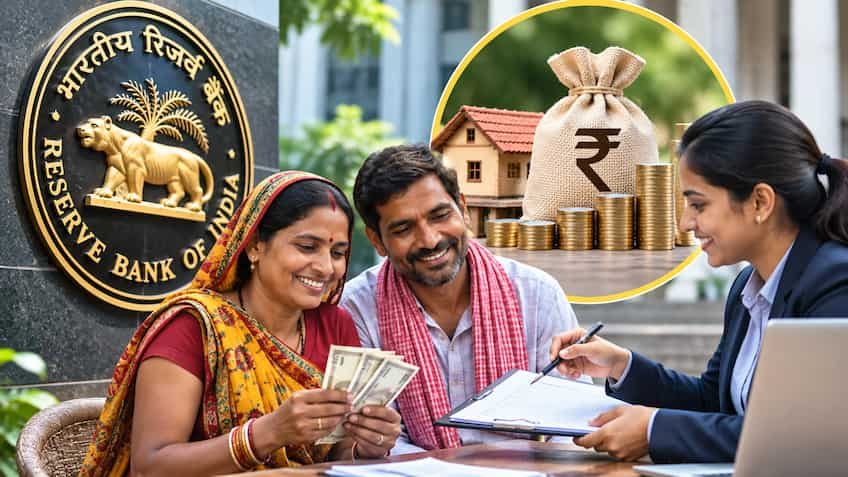
A very important signal has come from the Reserve Bank of India (RBI) for crores of small borrowers, street vendors, small shopkeepers and rural women self-help groups (SHGs) of the country. Under the current rules, the maximum limit of annual family income for collateral-free microfinance loans is fixed at ₹ 3 lakh. Now the central bank may consider reviewing this income limit of ₹3 lakh. RBI Deputy Governor S.C. Murmu (SC Murmu) has clarified that the regulator will consider revising the annual household income limit, if necessary, after assessing the changing needs of the industry, inflation and market developments. यदि आरबीआई इस सीमा को बढ़ाता है, तो निम्न-मध्यम आय वर्ग के लाखों नए परिवार भी बिना गारंटी वाले संस्थागत माइक्रोफाइनेंस कर्ज के दायरे में आ सकेंगे, जिससे उन्हें साहूकारों के ऊंचे ब्याज से बड़ी राहत मिलेगी।
जहां एक तरफ ₹3 लाख की इनकम लिमिट पर समीक्षा की उम्मीद जगी है, वहीं दूसरी तरफ माइक्रोफाइनेंस उद्योग की एक और बड़ी मांग को आरबीआई ने सिरे से खारिज कर दिया है। दरअसल, मौजूदा नियमों के तहत किसी भी माइक्रोफाइनेंस कर्जदार की कुल मासिक किस्तें (EMI) उसकी मासिक पारिवारिक आय के 50 प्रतिशत (FOIR – फिक्स्ड ऑब्लिगेशन टू इनकम रेशियो) से अधिक नहीं हो सकतीं। उद्योग जगत ने प्रस्ताव दिया था कि इस 50 प्रतिशत की गणना करते समय कुछ विशेष कर्जों के मूलधन (प्रिंसिपल) हिस्से को बाहर रखा जाए और केवल ब्याज को गिना जाए, ताकि ग्राहकों को अधिक लोन दिया जा सके। On this, Deputy Governor S.C. मुर्मू ने बेहद सख्त और स्पष्ट रुख अपनाते हुए कहा कि 50 प्रतिशत की सीमा पहले से ही काफी उदार है और इसमें किसी भी तरह की ढील देना इस नियम की मूल भावना के खिलाफ होगा। आरबीआई का मानना है कि कम आय वाले परिवारों के पास आर्थिक झटकों को सहने की क्षमता सीमित होती है, इसलिए 50 प्रतिशत की यह लक्ष्मण रेखा उन्हें अत्यधिक कर्ज (ओवर-इनडेटेडनेस) के जाल में फंसने से बचाती है और उनके रोजमर्रा के जीवनयापन के लिए पर्याप्त नकदी सुनिश्चित करती है।
To protect the interests of customers taking microfinance loans, RBI has already implemented many strict rules, which every borrower should be aware of. Under the rules, no bank or microfinance company can take any kind of lien on any property or deposit amount from you against the loan, because it is a completely collateral-free loan. Additionally, before sanctioning the loan, the lending company is required to provide the customer with a ‘Key Fact Statement’ (KFS) and loan card in simple language, clearly detailing the interest rate, processing fee and the total amount to be repaid. According to RBI guidelines, no recovery agent can call the borrower before 9 am and after 6 pm nor can he exert any kind of pressure or rude behavior. ऐसे में यदि भविष्य में आय सीमा बढ़ती है, तो ग्राहकों को केवल पंजीकृत बैंकों और आरबीआई द्वारा मान्यता प्राप्त एनबीएफसी-एमएफआई (NBFC-MFI) संस्थानों से ही अपनी वास्तविक आय दर्ज कराकर कर्ज लेना चाहिए।