 look news india

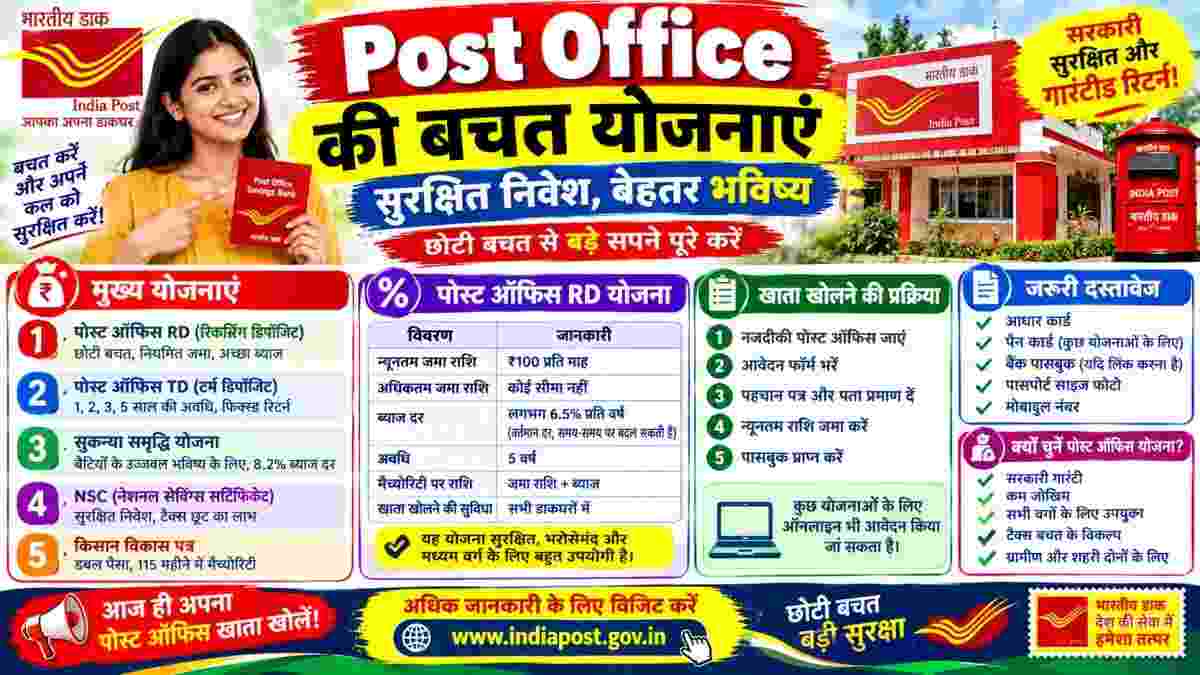
When it comes to safe investments and regular savings in the country, small savings schemes of post office still remain the choice of millions of people. The special thing is that these schemes have investment options for people of different ages, needs and financial status. If a person wants to prepare funds for the future by depositing a small amount every month, then Post Office RD Scheme can be useful for him. If you want to save for long term for your daughter’s education and marriage, then Sukanya Samriddhi Yojana (SSY) is an option. Similarly, Monthly Income Scheme (MIS) is available for investors seeking regular income every month.
Before investing in these post office schemes in the financial year 2026-27, it is important to understand their interest rate, deposit limit, maturity period and withdrawal rules. The central government reviews the interest rates of small savings schemes every three months. Therefore, before investing, the applicable quarterly rate must be checked.
In the order issued on September 30, 2026, the Finance Ministry has not made any change in the interest rates of small savings schemes for the third quarter of the financial year 2026-27 i.e. from October 1 to December 31, 2026. This means that the interest rates applicable in the July-September quarter will continue in the October-December quarter also.
The interest rates of major post office schemes are as follows:
| post office scheme | annual interest rate |
|---|---|
| post office savings account | 4.00% |
| Post Office RD (5 Years) | 6.70% |
| Post Office MIS | 7.40% |
| 1 year time deposit | 6.90% |
| 2 years time deposit | 7.00% |
| 3 years time deposit | 7.10% |
| 5 years time deposit | 7.50% |
| Senior Citizen Saving Scheme | 8.20% |
| Public Provident Fund (PPF) | 7.10% |
| Sukanya Samriddhi Yojana (SSY) | 8.20% |
| National Savings Certificate (NSC) | 7.70% |
| Kisan Vikas Patra (KVP) | 7.50% |
These rates are applicable from 1 October to 31 December 2026. There may be a change in interest rates after the new announcement of the government for the next quarter.
The Recurring Deposit (RD) scheme of the post office is useful for those who cannot invest a large lump sum but want to make regular savings every month. In this scheme, the account is opened for five years and a fixed amount has to be deposited every month.
At present, 6.70 percent annual interest is being given on five-year post office RD, which is calculated on quarterly compound basis. Investment in this scheme can be started with a minimum of Rs 100 per month. After this the deposit can be increased in multiples of Rs 10.
For example, if an investor deposits Rs 1,000 every month, his total deposit in five years will be Rs 60,000. Along with this, interest will also be available. The actual maturity amount will be determined as per the applicable interest rate and account terms.
RD scheme develops the habit of regular savings. In case of delay in depositing installment in the account, default fee may be imposed as per prescribed rules. If needed, eligible account holders can also choose the option of premature closure of the account with certain conditions.
Sukanya Samriddhi Yojana (SSY) has been launched especially with the aim of making the future of daughters financially secure. In this scheme, parents or legal guardians can open an account in the name of the eligible girl child.
This scheme is giving 8.20 percent annual interest in the quarter October-December 2026. This is one of the major high interest rates available in small savings schemes.
A minimum of Rs 250 and a maximum of Rs 1.50 lakh can be deposited in this scheme during a financial year. Generally the account can be opened before the girl child completes 10 years of age. Under the general rule, accounts can be opened for two daughters in a family, while there is a provision for special relaxation in cases involving twins or triplets born together.
The amount has to be deposited in SSY account for 15 years and maturity occurs after 21 years from the date of account opening. Partial withdrawal facility for higher education is also available under prescribed conditions. Therefore, this can be a long-term saving option for your daughter’s education and future major expenses.
If you want to invest your savings in a scheme where you get regular income in the form of interest every month, then you can consider Post Office Monthly Income Scheme (MIS).
7.40 percent annual interest is being given on MIS in the October-December 2026 quarter. The duration of this scheme is five years. In this, a maximum of Rs 9 lakh can be invested in a single account and a maximum of Rs 15 lakh can be invested in a joint account.
The specialty of this scheme is that the interest is paid every month. For example, on depositing Rs 9 lakh, the annual interest at the rate of 7.40 percent is Rs 66,600. That means you can get interest of around Rs 5,550 per month. Actual payment will be as per the rules of the scheme.
This scheme can be useful for people looking for regular income after retirement and investors who need interest every month. However, the monthly interest earned is normally taxable and prescribed deductions may be applicable on premature closure of the account.
Public Provident Fund (PPF) is a popular government scheme for long-term savings. In this, a minimum of Rs 500 and a maximum of Rs 1.50 lakh can be deposited in a financial year. Its basic tenure is 15 years.
At present 7.10 percent annual interest is being given on PPF. Interest is calculated on a monthly basis as per the prescribed minimum balance and is added to the account annually. Eligible investors may also get tax benefits under applicable income tax laws. After maturity, the option to extend the account as per the prescribed rules is available.
National Savings Certificate (NSC) is an investment option with a tenure of five years. It is getting 7.70 percent annual interest in the quarter October-December 2026. A minimum investment can be made in it from Rs 1,000 and thereafter the amount can be deposited in multiples of Rs 100. There is no limit on maximum investment. Eligible investors may also get tax benefits as per applicable rules.
Kisan Vikas Patra (KVP) is an option for investors who want to double their deposits within a stipulated period. At present, it is getting 7.50 percent annual interest. According to the current rate, the investment amount doubles in 115 months i.e. 9 years and 7 months. A minimum investment of Rs 1,000 can be made in this.
Senior Citizens Savings Scheme (SCSS) is designed for people aged 60 years and above. Retired persons between 55 and 60 years of age can also invest in it under certain prescribed conditions.
8.20 percent annual interest is being given on this scheme. Its tenure is five years and the maximum investment limit is Rs 30 lakh. In this, interest is paid on quarterly basis. This is an important option for people looking for regular interest income after retirement.
Post Office Time Deposit (TD) can be considered like a fixed deposit of a bank. In this, the amount can be deposited for a period of one, two, three and five years. Its interest rates for the October-December 2026 quarter are 6.90 percent, 7.00 percent, 7.10 percent and 7.50 percent respectively.
A minimum investment of Rs 1,000 can be made in this. Investing in a five-year time deposit can also provide tax benefits under the applicable income tax rules.
An account can be opened in Post Office Savings Account with a minimum of Rs 500. At present 4 percent annual interest is being given on this. This is useful for those who want to enjoy normal banking facilities while keeping their money safe. Eligible account holders can also avail facilities like net banking and e-passbook.
In most of the post office savings schemes, proof of identity and address, PAN card, Aadhar card, passport size photograph and necessary application forms can be asked to open an account. To open an account in the name of a minor, documents of the guardian are also required. Additional documents and eligibility conditions may vary depending on the scheme.
Before investing in post office schemes, it is important to understand your need, investment period and availability of money. RD can be useful for regular monthly savings, MIS for monthly interest income, SSY for daughter’s future and PPF for long term savings. Whereas NSC, KVP and Time Deposit provide investment options of different tenures.
Keep in mind that interest rates may change from time to time. Therefore, before investing, please confirm the latest rates, eligibility, withdrawal and tax related rules from the official website of India Post or your nearest post office. The decision to invest in any scheme should not be taken just by looking at the interest rate, but according to your financial needs and goals.