 look news india
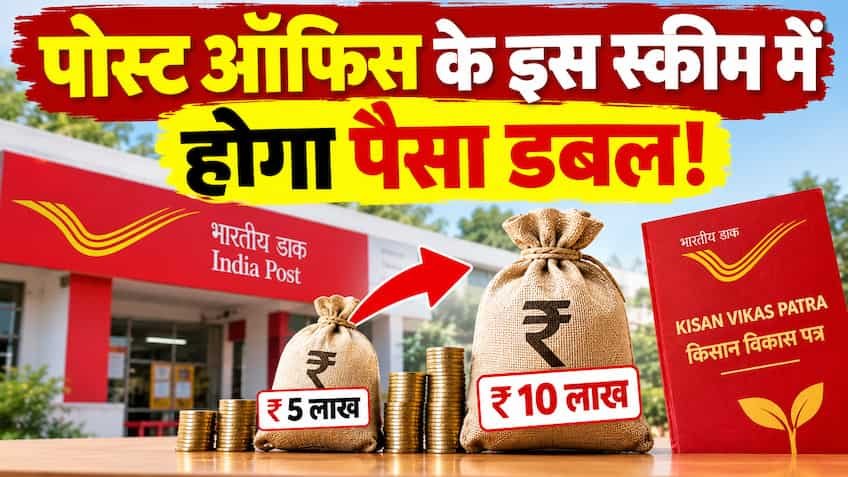
Post Office Kisan Vikas Patra (Kisan Vikas Patra – KVP) is one of the most trusted government savings schemes for investors looking for safe investments and fixed returns. This is a solid formula to double your savings without any market risk, away from the volatility of the stock market. Being backed by the Government of India, it comes with a 100% government security guarantee on your principal and returns.
-
annual interest rate: 7.5% (Compounded Annually)
-
Time for doubling of money: 115 months (ie 9 years and 7 months)
-
Minimum Investment: ₹1,000 (any amount in multiples of 100)
-
Maximum investment limit: No Upper Limit
| Deposit (Principal) | Interest rate (compounded annually) | maturity period | Total Maturity Amount (DOUBLED) | total interest profit |
| ₹1,00,000 | 7.5% | 115 months (9 years 7 months) | ₹2,00,000 | ₹1,00,000 |
| ₹5,00,000 | 7.5% | 115 months (9 years 7 months) | ₹10,00,000 | ₹5,00,000 |
| ₹10,00,000 | 7.5% | 115 months (9 years 7 months) | ₹20,00,000 | ₹10,00,000 |
| ₹15,00,000 | 7.5% | 115 months (9 years 7 months) | ₹30,00,000 | ₹15,00,000 |
If you deposit ₹5 lakh in lump sum, ₹10 lakh can be withdrawn directly from the post office on completion of 115 months.
-
Eligibility to open account: Any adult Indian citizen can open a joint account either singly or along with 3 adults. Parents can also open an account in the name of the minor.
-
Premature Closure: KVP has a lock-in period of 2 years 6 months (30 months). After completion of 30 months you can prematurely close the account as per the terms and conditions. Apart from this, premature withdrawal is also allowed on the death of the account holder or on court orders.
-
Loan facility: Secured loan can be easily obtained at low interest by pledging KVP certificate in any bank or financial institution as collateral/pledge.
-
No benefit of 80C: No tax exemption is available on the amount deposited in Kisan Vikas Patra under Section 80C of the Income Tax Act.
-
Tax on interest: The interest received from KVP is taxable and is taxed as per your tax slab by adding it to your ‘Income from Other Sources’.
-
TDS deduction: No TDS is deducted by the post office at the time of withdrawal, however the investor has to self-declare this income while filing the return.