 look news india
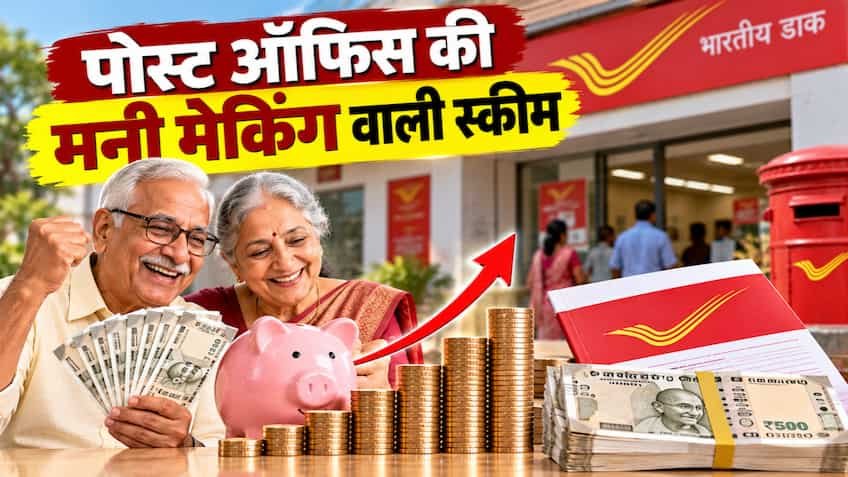
Indian Post Office savings schemes have always been the first choice for those looking for a safe, guaranteed and fixed return investment option away from the fluctuations of the stock market and the market risks of mutual funds. In today’s time, the biggest question among the middle class and working people is that without investing huge amount in lump sum, how to create a strong and big fund by making small savings every month. Recently Post Office 5 Year Recurring Deposit i.e. Recurring Deposit (National Savings Recurring Deposit Account – RD) The scheme has come into the center of discussion. The biggest feature of this scheme is that you do not need to deposit lakhs of rupees in lump sum, rather you can create a huge fund of more than Rs 10 lakh by saving just ₹ 200 daily (i.e. ₹ 6,000 per month). The most surprising thing in this is that out of this total fund, you do not have to invest more than Rs 3 lakh from your pocket, rather it is directly added to your account in the form of government interest. Being equipped with Sovereign Guarantee, there is zero risk of losing every penny in this scheme.
The 5-year RD scheme of the post office is designed to inculcate the habit of regular savings among small investors. Currently the Central Government is on this 5 year RD 6.7 percent per year It is offering attractive interest of Rs., which is calculated as Quarterly Compounding interest. In this scheme, an account can be opened with a minimum of ₹ 100 per month and no upper limit has been fixed for the maximum deposit amount. Any adult citizen of the country can open a single account by going to his nearest post office, or husband and wife can also operate a joint account. Parents can also open this account in the name of their minor children above 10 years of age. The official maturity period of this scheme is 5 years (60 months), but under the post office rules, the account holder gets the special facility that after completion of 5 years, he can extend this account for next 5 more years (total 10 years) by applying in the concerned post office.
It is very interesting to understand the complete financial analysis of how a daily savings of ₹ 200 can generate a profit of more than ₹ 3 lakh on the basis of interest alone. If you save ₹200 every day, your monthly deposit comes to ₹6,000. When you deposit this monthly installment continuously for 5 years (60 months), the total invested capital from your pocket is ₹3,60,000 (Rs 3.60 lakh). At an interest rate of 6.7% per annum (compounded quarterly), a total maturity amount of ₹ 4,28,197 is generated in your account after 5 years, which includes interest of approximately ₹ 68,197. The real miracle happens when instead of withdrawing this money, you extend the account for another 5 years and continue the installments of ₹6,000 per month. On completion of 10 years (120 months), the total deposit in your pocket will be ₹7,20,000 (Rs 7.20 lakh). At the same time, the total net interest received in 10 years has increased to almost ₹3,06,131 (approximately ₹3.06 lakh) Will cross the figure of Rs. Thus after 10 years the total amount in your hand ₹10,26,131 (more than Rs 10.26 lakh) Guaranteed fund of Rs.
Post Office RD Scheme also provides loan facility to investors to overcome cash crunch in times of emergency financial needs. If your account has been running smoothly for 12 consecutive months (1 year) and at least 12 installments have been deposited, you can take a loan up to 50 percent of the total balance in your account. The interest charged on this loan is only 2 percent more than the applicable RD interest rate, which can be repaid in lump sum or in easy installments. As far as closure of the account is concerned, pre-mature closure is allowed after completion of three years (36 months), but keep in mind that on premature closure of the account, you get interest only at the rate of 4% instead of 6.7% of Ordinary Post Office Savings Account. Therefore, to avail the full benefit of interest, it is the wisest decision to keep the account running for full 5 or 10 years.
Maintaining discipline is the most important condition while investing in Post Office RD. If your account is opened between 1st and 15th of the month, you have to deposit your monthly installment by 15th of every month. Whereas if the account is opened after 16th, then there is exemption to deposit the installment till the last working day of the month. If for some reason you forget to deposit the installment by the due date, the post office charges a default fee (penalty) of ₹1 per month for every ₹100. If installments are not deposited for four consecutive months, the account is declared ‘default’ and a penalty has to be paid along with the outstanding installments to revive it. The easiest way to avoid this hassle is to set up an auto-debit (Standing Instruction) from your post office savings account or IPPB mobile banking app, so that your installment gets automatically deducted on the fixed date every month.
The process of opening a 5-year RD account in the post office is extremely simple and free from paper hassles. For this, the applicant has to go to his nearest post office and fill the RD account opening form. Self-attested photocopies of Aadhar Card and PAN Card have to be attached with the form as proof of identity and address. Apart from this, it is mandatory to give two passport size color photographs and complete details of the nominee. The passbook can be obtained by depositing the first installment through cash or cheque. If you have an India Post Payments Bank (IPPB) account, you can also deposit your RD installment every month digitally through mobile banking from the comfort of your home. This scheme is an ideal financial shield for all those who want to convert their hard-earned money into a huge fund of Rs 10 lakh without taking the risk of stock market only due to interest.